The ongoing process regarding the divestment of shares in PT Freeport Indonesia (PTFI) has once again brought the strategic management of Indonesia’s vast natural resources into sharp focus. As the government navigates the intricate legal, financial, and operational pathways required to increase national ownership in the massive Grasberg copper and gold mine located in Papua, state-owned enterprises (SOEs) have emerged as the primary vehicles for this historic acquisition. Specifically, state-owned mining and mineral enterprises PT Aneka Tambang (Persero) Tbk (ANTM), commonly known as Antam, and PT Inalum (Persero) have been positioned to spearhead the acquisition of the divested shares.
Amid public debates and questions concerning the financial capacity and technical expertise required to manage an operation of such unprecedented scale, high-ranking government officials have expressed unwavering confidence in the capabilities of Indonesia’s state-owned corporate sector. Highlighting the established track record of domestic mining conglomerates, the Ministry of Finance has firmly rejected notions that local entities lack the institutional maturity or technical know-how to successfully oversee one of the most lucrative and complex mining operations in the global extractive industry.
Background Context of the Freeport Indonesia Divestment
The question of sovereign ownership over PT Freeport Indonesia has remained a central pillar of Indonesian economic nationalism and regulatory policy for decades. Operating under a succession of Contracts of Work (CoW) originally signed during the late 1960s, Freeport-McMoRan, the US-based parent company of PTFI, held extensive rights to explore, extract, and process the rich mineral deposits of the Sudirman Mountain Range in Papua. While the venture contributed significantly to regional employment, state revenues, and infrastructure development, domestic critics and successive administrations long argued that the contractual terms disproportionately favored foreign corporate interests while returning suboptimal economic benefits to the Indonesian state.
A significant turning point in this protracted dynamic occurred with the introduction of Law No. 4 of 2009 on Mineral and Coal Mining. This landmark legislation fundamentally altered the regulatory framework by mandating that foreign-owned mining companies progressively divest their shares to domestic stakeholders—including the central government, regional governments, state-owned enterprises, regional-owned enterprises, and private national entities—until domestic ownership reached a minimum threshold of 51 percent.
The implementation of these divestment mandates, however, was fraught with prolonged negotiations, regulatory disputes regarding the transition from a Contract of Work to a Special Mining Business License (IUPK), and complex valuations of underground reserves. As the deadline for compliance approached during the mid-2010s, the Indonesian government formulated a strategic consortium of state-owned enterprises to ensure that the equity would be absorbed directly by the state, thereby securing long-term national control over strategic economic assets.
Chronology of State Consolidation and Divestment Efforts
The trajectory leading to the positioning of PT Aneka Tambang and PT Inalum as the designated buyers of the Freeport shares involved a carefully calculated sequence of policy formulations, inter-ministerial coordination, and corporate restructuring.
In the years immediately following the enactment of the 2009 Mining Law, the Indonesian government incrementally intensified pressure on PT Freeport Indonesia to outline a clear divestment schedule. Initially, the dispute centered on the exact percentage of shares to be offered and the valuation methodology applied to future mineral reserves.
By late 2015, the divestment process entered a critical phase. Regulatory requirements stipulated that Freeport-McMoRan was obligated to offer an additional 10.64 percent of its shares to the Indonesian government, building upon a prior 9.36 percent stake already held by the state. This brought the total targeted government acquisition to 20 percent at that specific juncture, serving as a stepping stone toward the ultimate goal of majority control.
During this period, the Ministry of Finance, through the Directorate General of State Assets (DJKN), evaluated the financial readiness of various state institutions. It was determined that a unified approach utilizing the balance sheets and operational expertise of established mining SOEs offered the most viable pathway. PT Aneka Tambang (Persero) Tbk, with its extensive portfolio in gold, nickel, and bauxite mining, along with PT Inalum (Persero)—which was progressively being groomed to function as the strategic holding company for all state-owned mining assets—were selected as the primary financial pillars for the transaction.
This institutional framework laid the groundwork for subsequent milestones, including the eventual landmark agreement in late 2018 where Inalum successfully acquired a 51.23 percent majority stake in PT Freeport Indonesia through a complex transaction valued at USD 3.85 billion.
Official Responses and Government Assurances
Addressing lingering public skepticism regarding the operational and financial readiness of Indonesian state enterprises to absorb and manage the complex mining infrastructure of Freeport, Director General of State Assets at the Ministry of Finance, Sonny Loho, delivered a resolute defense of domestic corporate competence. Speaking in Jakarta, Loho emphasized that domestic mining companies had achieved a high degree of maturity, professional governance, and technical proficiency.
"Yes, they are capable, there is no reason to doubt them. Our mining companies are already performing very well," Loho stated at the Ministry of Finance.
He further urged stakeholders, market observers, and the general public to discard unwarranted anxieties concerning the management transition at the Grasberg complex. According to Loho, historical hesitation often stems from an underestimation of Indonesian technical capabilities rather than any genuine operational deficiencies within the state-owned sector.
"There is no need to worry. People in Indonesia worry too much; we must be bold. We have to be able to manage it," he added, emphasizing that the mastery of complex industrial processes is a natural evolutionary step for a nation endowed with vast mineral wealth.
This sentiment was echoed across various levels of the government and the Ministry of State-Owned Enterprises (SOEs). Officials consistently maintained that the consolidation of mining assets under a unified holding structure would optimize capital allocation, enhance operational synergies, and ensure that environmental and social responsibilities in Papua were met with greater accountability compared to previous private management models.
Supporting Data and Financial Frameworks
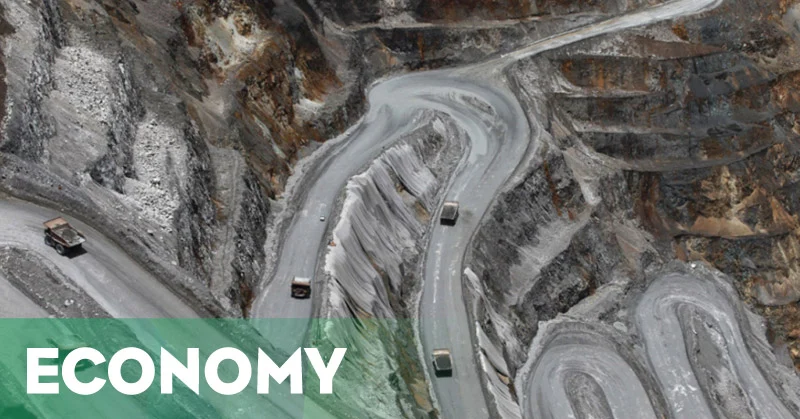
The sheer magnitude of the Freeport Indonesia operations necessitates robust financial planning and sophisticated risk management by any entity seeking to acquire and manage its equity. The Grasberg mine represents one of the largest copper and gold deposits globally, characterized by massive open-pit and deep underground block-caving mining techniques that demand continuous, high-volume capital expenditures.
Prior to the finalization of the majority acquisition, financial analysts scrutinized the balance sheets of both Antam and Inalum. Antam, listed on the Indonesia Stock Exchange (IDX: ANTM), brought decades of operational experience in precious and base metals extraction, maintaining rigorous compliance with international environmental and governance standards. Inalum, on the other hand, possessed significant capital-raising capabilities, which were subsequently demonstrated when the holding company successfully secured billions of dollars in international bonds and syndicated loans to finance the 2018 buyout without placing an undue fiscal burden directly on the state budget.
Data from the Ministry of Energy and Mineral Resources indicated that PTFI consistently generated substantial revenues, contributing significantly to non-tax state revenues (PNBP), corporate income taxes, regional development funds, and royalty payments. By channeling these financial flows directly into state-owned balance sheets, the consolidation model aimed to create a self-sustaining fiscal loop where profits derived from national resources could be reinvested into national infrastructure, industrial downstreaming initiatives, and regional development programs in Papua.
Broader Economic Impact and Strategic Implications
The integration of PT Freeport Indonesia into the state-owned enterprise ecosystem carries profound implications for the domestic economy, the industrial downstreaming agenda, and Indonesia’s standing in the global mineral supply chain.
From a macroeconomic perspective, majority state ownership ensures that a greater share of the economic value generated from non-renewable natural resources remains within the country. Rather than profit repatriation by foreign entities, dividends distributed by PTFI directly bolster state revenues, supporting national development priorities, poverty alleviation programs, and public infrastructure projects.
Furthermore, the transition aligns closely with Indonesia’s national policy on mineral downstreaming. For decades, raw concentrates extracted from Papua were largely shipped abroad for smelting and refining. Under state stewardship, coordinated through the mining holding ecosystem, increased emphasis has been placed on expanding domestic processing capabilities—exemplified by the construction and operation of major domestic smelters, such as the Manyar smelter in East Java. This ensures that the country captures higher economic value-add at every stage of the production chain, transforming raw mineral extraction into a catalyst for domestic industrialization.
Operationally, the transition has also necessitated heightened commitments to environmental stewardship, sustainable mining practices, and corporate social responsibility (CSR) programs targeted specifically at local Papuan communities. By embedding national developmental objectives into the core corporate mandate of PTFI, the government sought to foster long-term social stability, enhance local workforce participation, and ensure that the economic benefits of resource extraction are equitably distributed among the indigenous populations of the region.
Ultimately, the confidence expressed by financial and regulatory authorities in the capabilities of BUMNs to manage world-class mining assets reflects a broader paradigm shift in Indonesia’s economic sovereignty. The successful navigation of the Freeport divestment process stands as a testament to the maturation of domestic corporate governance, marking a definitive chapter in the nation’s efforts to independently direct its economic destiny through strategic state enterprise management.