The future of American mining giant PT Freeport Indonesia remained shrouded in administrative uncertainty as Coordinating Minister for Economic Affairs Darmin Nasution asserted that formal discussions regarding the company’s contract extension and subsequent share divestment were far from finalized. Speaking to academics and journalists at the University of Indonesia, Minister Darmin addressed mounting public and political curiosity surrounding the timeline of the divestment process, emphasizing that the overarching legal and contractual framework must first reach a definitive conclusion.
The statement underscored the complex bureaucratic, legal, and economic dynamics that have long characterized the relationship between the Indonesian government and the multinational mining corporation. At the heart of the discourse was the controversial requirement for foreign-owned mining entities operating within Indonesian jurisdiction to divest a portion of their equity to domestic stakeholders—a policy designed to ensure greater national sovereignty over strategic natural resources while balancing foreign investment incentives.
Background Context of the Freeport Contract and Divestment Obligations
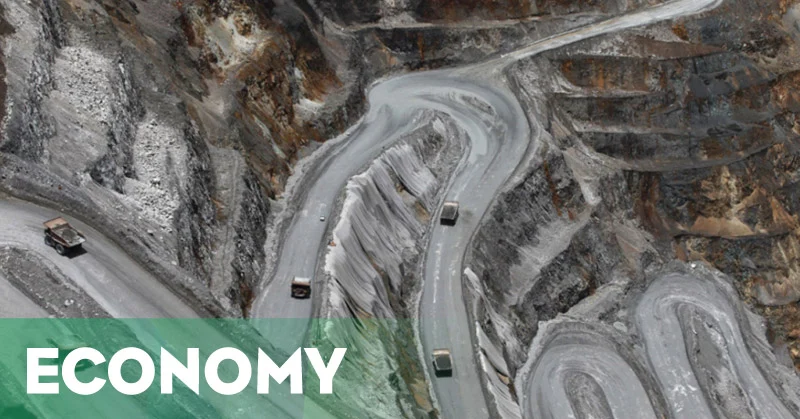
PT Freeport Indonesia, a subsidiary of the United States-based Freeport-McMoRan Copper & Gold Inc., has operated the massive Grasberg mine in Papua—one of the largest gold and copper deposits in the world—for decades. Under the prevailing regulatory frameworks, particularly Government Regulation (PP) No. 77 of 2014 concerning the Third Amendment to Government Regulation No. 23 of 2010 on the Implementation of Mineral and Coal Mining Business Activities, foreign mining companies operating underground or open-pit mines in Indonesia are subjected to strict divestment obligations.
Specifically, foreign entities are legally mandated to progressively divest their shares to domestic entities until Indonesian ownership reaches at least 51 percent. This regulation serves as a cornerstone of the country’s resource nationalism policy, aiming to redirect a greater share of mining revenues into state coffers, empower state-owned enterprises (SOEs), and foster local economic participation. However, the implementation of these rules has frequently sparked tense negotiations between Jakarta and corporate executives based in Phoenix, Arizona. The focal point of contention often revolves around asset valuation, the precise timing of share offerings, and the legal security of long-term operational contracts.
Chronology of Events Leading to the Impasse
The friction surrounding the 2015 divestment timeline can be traced back to a series of regulatory mandates and deadlines established by the Indonesian Ministry of Energy and Mineral Resources. According to the regulatory framework in place, October 14, 2015, marked a critical legal milestone: the date by which Freeport was officially required to commence the process of offering its shares to the Indonesian government.
The initial divestment tranche stipulated that Freeport must release 10.64 percent of its total equity to local buyers. This offering was structured around a strict hierarchy of priorities designed to maximize national interest. First in line for the acquisition of the divested shares was the central government. Should the central government decline or fail to secure the purchase within a specified timeframe, the priority shifted secondly to state-owned enterprises (BUMN). If state-owned enterprises similarly passed on the opportunity, the acquisition rights would then cascade down to regionally-owned enterprises (BUMD), and finally, as a last resort, to private national entities, which could include conducting an initial public offering (IPO) on the domestic stock exchange.
Despite the clarity of the legal framework, Freeport effectively delayed the execution of the October 2015 divestment deadline. Representatives of the mining giant argued that they were awaiting formal revisions to Government Regulation 77 of 2014. The company sought greater regulatory certainty, particularly concerning how share valuations would be calculated and whether the anticipated contract extensions would be granted concurrently with the divestment process. This delaying tactic drew criticism from various domestic political factions and economic observers, who viewed the maneuver as an attempt by the multinational corporation to retain maximum equity control for as long as possible while leveraging its economic footprint in Papua.
Minister Darmin Nasution’s Official Stance and Analysis
Weighing in on the unfolding deadlock, Coordinating Minister for Economic Affairs Darmin Nasution adopted a cautious yet pragmatic tone. When pressed by reporters on whether the government was actively evaluating pathways such as an initial public offering to absorb the 10.64 percent stake, Darmin clarified that such financial mechanisms were premature.
"Freeport’s process itself is not yet finished regarding the matter of the extension; perhaps that will be addressed later in that phase," Darmin stated during his visit to the University of Indonesia.
The minister further elaborated that any potential divestment strategy—whether executed through a direct placement to state entities or via a public offering on the capital market—demanded rigorous academic and administrative scrutiny. "That (whether through an IPO or otherwise) must be studied more deeply," he added, signaling that the cabinet was not prepared to rush into financial transactions without comprehensive risk assessments and inter-ministerial coordination.
Economic and Strategic Implications for Indonesia
The ongoing saga surrounding PT Freeport Indonesia carries profound economic, financial, and political implications for the Southeast Asian nation. From a fiscal perspective, the Grasberg mine generates substantial state revenues through corporate taxes, royalties, and export duties. Ensuring a transparent and equitable divestment process is viewed by economic analysts as vital for maximizing the long-term public benefit of non-renewable natural resources.
Furthermore, the handling of the Freeport contract renegotiations serves as a litmus test for Indonesia’s investment climate. While the government is keen to project a strong stance on resource nationalism and domestic equity participation, it must simultaneously navigate the delicate balance of maintaining investor confidence. Foreign direct investment remains a critical pillar of Indonesia’s macroeconomic growth strategy, and sudden, abrasive regulatory shifts can easily spook international capital markets.
The debate over the valuation methodology also poses significant hurdles. Valuing a massive, highly complex mining operation like Grasberg requires intricate financial auditing, future commodity price forecasting, and assessments of environmental liabilities. If the valuation is set too high, state-owned enterprises may struggle to finance the acquisition without incurring unsustainable debt burdens. Conversely, if the valuation is set too low, it risks sparking legal disputes and international arbitration claims from the corporate shareholder base.
Broader Industry Reactions and Future Outlook
As the government continues its deliberations, various stakeholders within the political and economic spheres have voiced divergent perspectives. Industry associations generally advocate for a collaborative approach that respects existing contractual agreements while honoring domestic laws. Meanwhile, nationalist politicians and labor unions consistently push for a harder line, demanding immediate state acquisition of a majority stake to ensure that the wealth extracted from Papuan soil directly benefits the broader Indonesian populace.
The statement by Minister Darmin Nasution effectively poured cold water on immediate expectations of a swift resolution. By declaring that the core extension process remained incomplete, the government signaled that all related components—including equity divestment, environmental reclamation commitments, and local smelter construction obligations—would be bundled together into a comprehensive overarching agreement.
Ultimately, the resolution of the Freeport contract extension and divestment impasse will set a crucial precedent for how Indonesia manages its strategic natural resource sector for decades to come. As administrative reviews, inter-ministerial talks, and legal adjustments grind forward, the eyes of the domestic public, financial markets, and international investors remain firmly fixed on Jakarta, awaiting the next decisive chapter in one of the country’s most high-stakes economic dramas.