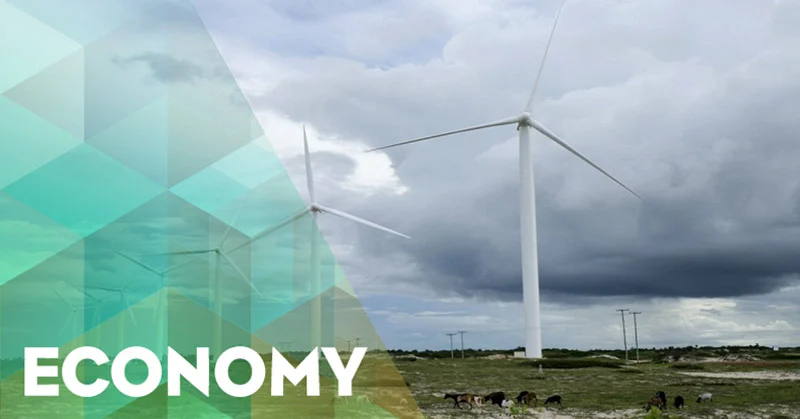
Jakarta — Amid escalating global discussions regarding climate change, sustainable development, and long-term energy security, the Indonesian government faced mounting pressure to reduce its heavy reliance on fossil fuels. In November 2015, the Coordinating Minister for Maritime Affairs and Resources, Rizal Ramli, forcefully underscored the urgent need for comprehensive energy diversification. Speaking from his office in Jakarta on Monday, November 9, 2015, Ramli emphasized that Indonesia must transition away from its traditional dominance of coal-fired power generation and aggressively foster alternative, renewable energy sources, particularly geothermal power, solar energy, and hydroelectricity.
Despite decades of academic discourse, policy frameworks, and international commitments to embrace green energy, the nation’s practical execution had historically lagged behind its ambitious rhetoric. Ramli’s statements brought to the forefront a persistent paradox within Indonesia’s energy landscape: while the archipelago possesses some of the world’s richest renewable energy reserves, the actual realization of these projects remains notably sluggish. Industry analysts, policymakers, and investors alike turned their attention to the structural impediments—chiefly regulatory hurdles and unappealing economic incentives—that have continuously stifled the clean energy sector in Southeast Asia’s largest economy.
The urgency of Ramli’s push for diversification was not born in a vacuum. It was the culmination of years of growing environmental awareness, domestic energy demand spikes, and shifting global financial priorities that began prioritizing sustainability over carbon-heavy extraction industries.
The Historical Backdrop of Indonesia’s Energy Matrix
For decades, Indonesia’s power generation strategy relied heavily on coal. Blessed with vast coal deposits, particularly in Sumatra and Kalimantan, the country capitalized on this cheap and abundant resource to fuel its rapid industrialization and electrify millions of households. Coal quickly became the backbone of the state-owned electricity company, Perusahaan Listrik Negara (PLN), ensuring steady, low-cost baseline power.
However, this heavy reliance created a vulnerability. As global pressure mounted to curb greenhouse gas emissions—culminating in international climate summits such as the upcoming COP 21 in Paris—Indonesia found itself under intense scrutiny. Environmental organizations and international partners repeatedly pointed out that Indonesia’s Nationally Determined Contributions (NDCs) would be nearly impossible to meet without a fundamental shift in its power generation portfolio.
Furthermore, economists warned of the "resource curse" and the financial volatility associated with fossil fuel subsidies and global commodity price fluctuations. Transitioning to renewables was no longer viewed merely as an environmental imperative, but as a strategic economic necessity to insulate the country from global energy shocks.
The Geothermal and Renewable Paradox
Indonesia sits squarely atop the Pacific Ring of Fire, endowing the country with an estimated 40% of the world’s total geothermal energy reserves, roughly equivalent to 29 gigawatts (GW) of potential power generation capacity. In addition to geothermal wealth, the equatorial nation enjoys abundant year-round solar irradiation, vast biomass potential, and numerous river networks capable of supporting both large-scale and micro-hydro power plants.
Yet, despite this staggering natural endowment, the utilization rate remained dismally low. As of late 2015, Indonesia had harnessed only a minor fraction of its geothermal potential. During his address, Ramli candidly pointed out the discrepancy between policy aspirations and field realities.
"We are currently discussing, still discussing, and there have already been many discussions, speeches, and lectures stating that Indonesia must diversify its energy matrix, shifting from coal to other sources, including renewables," Ramli stated. "However, only very few have actually been built—whether they are water sources or geothermal. We are discussing why this is the case."
The stark realization that new installations were moving at a snail’s pace prompted the Coordinating Ministry to investigate the root causes holding back both domestic and foreign capital deployment.
Unpacking the Investor Dilemma: The Pricing Problem
The core obstacle identified by Ramli and his economic team centered on market economics, specifically the structure of feed-in tariffs and power purchase agreements (PPAs). For renewable energy projects—which typically require high upfront capital expenditures (CapEx) but feature low operating costs—predictable, attractive, and secure long-term pricing is vital for risk mitigation.
At the time, independent power producers (IPPs) routinely cited bureaucratic red tape, prolonged licensing procedures, and unfavorable electricity pricing caps set by the government and PLN as major deterrents. Because coal power was heavily subsidized and historically cheaper to produce on a short-term accounting basis, renewable energy tariffs struggled to compete on a level playing field without robust government intervention.
"We suspect that the pricing structure is simply not attractive," Ramli remarked. "The pricing must be made attractive so that investors are genuinely willing to pour capital into geothermal and solar energy."
Investors demanded regulatory certainty, fair risk-sharing mechanisms, and tariffs that reflected the true lifecycle cost and environmental benefits of clean energy. Without these adjustments, private capital—which was desperately needed since state budgets alone could not finance the multi-billion-dollar green transition—would continue to bypass Indonesia in favor of more predictable regional markets.
Stakeholder Reactions and Institutional Hurdles
The debate sparked varied responses across Indonesia’s complex institutional framework. Ministry of Energy and Mineral Resources (ESDM) officials, along with representatives from PLN, faced mounting pressure to overhaul existing regulatory frameworks.
Environmental groups welcomed Ramli’s frank assessment, noting that public acknowledgment of the pricing barrier was a crucial first step. For years, advocacy groups had argued that artificially suppressed electricity tariffs for renewable energy favored fossil fuel incumbents. They urged the government to implement progressive feed-in tariffs and streamline the complicated permitting process that often saw geothermal exploration trapped in bureaucratic limbo for years.
Conversely, financial analysts pointed out the delicate balancing act facing the government. While higher tariffs would incentivize private investment, they also threatened to increase the financial burden on PLN, which was already strained by subsidy obligations and the high cost of maintaining a nationwide grid. Crafting a sustainable financing model that attracted foreign direct investment (FDI) without overburdening state finances or spiking electricity prices for retail consumers remained the ultimate policy challenge.
Broader Implications for Indonesia’s Economic and Environmental Future
The implications of successfully diversifying Indonesia’s energy mix extend far beyond environmental conservation. A strategic pivot toward renewables carries profound macroeconomic and geopolitical consequences.
First, energy security is inextricably linked to national sovereignty. By maximizing domestic geothermal and solar assets, Indonesia can significantly reduce its exposure to imported fossil fuels, stabilizing its trade balance and protecting its foreign exchange reserves against global oil and coal price shocks.
Second, the green energy transition represents a massive economic opportunity. Developing a robust domestic renewable energy sector can catalyze high-tech manufacturing, create hundreds of thousands of green-collar jobs, and foster technological innovation. Regions rich in geothermal resources—often located in outer islands outside the main economic hub of Java—stand to benefit immensely from decentralized electrification, which drives local economic development and reduces regional inequality.
Finally, meeting global climate commitments enhances Indonesia’s standing in international diplomacy. As global supply chains increasingly demand green credentials, countries that rely heavily on dirty energy risk facing carbon border adjustments and trade penalties from export partners, particularly in the European Union and North America. Embracing clean energy is thus essential for maintaining the global competitiveness of Indonesian exports.
Conclusion and the Path Forward
The candid admissions by Coordinating Minister Rizal Ramli in November 2015 marked a critical turning point in the national discourse on energy policy. By openly identifying pricing unattractiveness and implementation bottlenecks as the primary culprits behind the sluggish growth of renewables, the government signaled a willingness to confront structural inefficiencies head-on.
While the transition from a coal-dependent economy to a diversified, green energy leader was undeniably fraught with financial, regulatory, and institutional challenges, the long-term trajectory was clear. For Indonesia to achieve sustainable economic growth, protect its environment, and secure its energy future, the imperative laid out by Ramli remained absolute: the nation had to look beyond coal and unlock the vast, untapped potential of its renewable resources.