The ongoing divestment process of PT Freeport Indonesia (PTFI) marked a significant milestone as the Indonesian government prepared state-owned enterprises to take a decisive stake in the massive mining operations in Papua. Amid public debates concerning technical readiness, financial capability, and operational management, high-ranking government officials expressed absolute confidence in the country’s corporate capacity. Specifically, the Ministry of Finance asserted that Indonesian state-owned mining entities possessed both the technical expertise and the financial maturity required to manage one of the largest gold and copper mines in the world successfully.
This assertion followed strategic maneuvers by the government to designate specific state-owned enterprises as the primary vehicles for the acquisition. As the divestment discussions progressed through various regulatory and corporate channels, national attention remained fixed on whether domestic institutions could shoulder the immense responsibilities historically handled by multinational mining conglomerates.
State-Owned Enterprises Targeted for Acquisition
The focal point of the divestment strategy involved two prominent Indonesian State-Owned Enterprises (BUMN): PT Aneka Tambang (Persero) Tbk, commonly known as Antam, and PT Inalum (Persero). These entities were chosen due to their established track records in the minerals and metals sector, as well as their strategic alignment with national resource sovereignty goals.
PT Aneka Tambang Tbk, a diversified mining and metals company operating primarily in nickel, gold, and bauxite, brought decades of operational experience within the domestic regulatory landscape. Meanwhile, PT Inalum (Persero), which later evolved into the holding company MIND ID (Mining Industry Indonesia), possessed the strategic investment capacity required for large-scale capital acquisitions.
The strategy to position these state-owned enterprises as the prospective buyers of the divested shares aligned with Article 33 of the 1945 Indonesian Constitution, which dictates that the nation’s vital natural resources must be utilized for the maximum prosperity of the people. By channeling ownership through state corporations, the government aimed to increase national economic leverage, secure higher state revenues, and ensure greater oversight over environmental and social policies surrounding the Grasberg mine in Mimika, Papua.
Government Confidence and Official Stances
Addressing reporters at the Ministry of Finance in Jakarta, Director General of State Assets Sonny Loho firmly dismissed skepticism regarding the capabilities of Indonesian state-owned enterprises to manage the Freeport concessions. His remarks served as a direct reassurance to financial markets, lawmakers, and the public, all of whom scrutinized the intricate mechanics of the divestment proceedings.
"Yes, they are capable. There is no reason to doubt them. Our mining companies are already performing very well," Sonny stated, addressing concerns about corporate readiness.
He further emphasized that domestic stakeholders needed to overcome an internal reluctance or hesitation when confronting multinational-scale operations. Urging a confident approach toward national asset management, he added, "There is no need to worry. Indonesians tend to worry too much; we must be bold. They have to be able to manage it."
Sonny’s statements reflected a broader administrative push within the Indonesian government to assert greater control over strategic economic sectors. Over the preceding decades, the operation of the Grasberg mine by Freeport-McMoRan had been a subject of intense political and economic debate, with critics arguing that Indonesia received an inadequate share of the economic benefits relative to the extraction volume. The impending acquisition by state-owned enterprises represented a structural shift designed to rectify these historical imbalances.
Background Context of the Freeport Divestment
The context surrounding the involvement of Antam and Inalum dates back to long-standing negotiations between the Indonesian government and US-based mining giant Freeport-McMoRan Inc., the parent company of PT Freeport Indonesia. For decades, PTFI operated under a Contract of Work (CoW) system established during the early years of the New Order regime. While the mine generated substantial foreign exchange and employment, political pressure mounted steadily within Indonesia to renegotiate the terms of the contract to secure a higher equity stake for the host nation.
Under prevailing mining regulations, foreign-owned mining companies operating in Indonesia were legally required to divest a certain percentage of their shares to Indonesian entities—encompassing the central government, regional governments, and state-owned or private national enterprises. The divestment process was designed as a gradual transition of ownership, intended to ensure that the host country ultimately secured majority control upon the expiration or renegotiation of long-term operational permits.
The transition from a Contract of Work to a Special Mining Business License (IUPK) framework served as the legal catalyst for these divestment obligations. This regulatory overhaul required Freeport to relinquish its old contract terms in exchange for extended operating rights up to 2041, conditional upon the construction of domestic smelting facilities and the successful divestment of up to 51 percent of its shares to Indonesian entities.
Chronology of Key Events Leading to the State-Owned Acquisition
The path toward state consolidation of PT Freeport Indonesia shares involved a complex series of political, legal, and financial milestones.
In 2014, the Indonesian government introduced strict mineral export bans under the 2009 Mining Law, aimed at compelling mining companies to build domestic processing plants rather than exporting raw ores. This policy triggered protracted negotiations and temporary export suspensions for PTFI.
By 2015, the divestment schedule stipulated under the existing contractual agreements entered a critical phase. PT Freeport Indonesia was obligated to offer a specific percentage of its shares to Indonesian participants at fair market value. During this period, the central government designated state-owned enterprises—specifically Antam and Inalum—as the prime institutional candidates to absorb these equity offerings.
Subsequent developments in the following years saw the government transition from acquiring minority stakes to securing a controlling majority. In late 2018, Inalum executed a historic transaction totaling USD 3.85 billion to acquire a 51.23 percent majority stake in PTFI, effectively cementing the role of state-owned enterprises as the primary custodians of the nation’s premier mining assets. The foundational groundwork laid in late 2015 by financial authorities, including the assertions of operational competence voiced by officials like Sonny Loho, proved pivotal in building domestic consensus for these sweeping financial transactions.
Supporting Data and Market Dynamics
Evaluating the capability of Indonesian state-owned enterprises to manage assets of this magnitude requires an examination of financial capacity, technical proficiency, and macroeconomic impact. At the time of the divestment discussions, PT Aneka Tambang Tbk and PT Inalum (Persero) maintained substantial asset portfolios, although the sheer scale of the Freeport acquisition required sophisticated syndication and international financing structures.
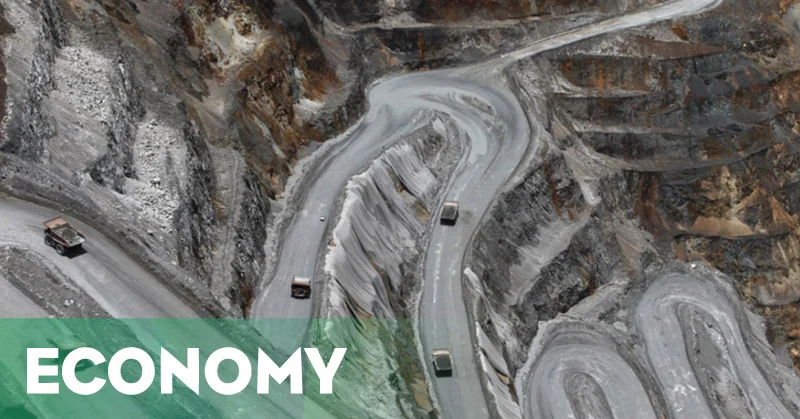
The Grasberg complex stands as one of the world’s largest copper and gold deposits, producing millions of ounces of gold and hundreds of thousands of tons of copper annually. Managing such a vast enterprise entails complex underground mining engineering, high capital expenditures, rigorous environmental management standards, and the management of a massive workforce in a remote region.
While private sector proponents argued that multinational operators possessed superior technological access, financial analysts noted that Indonesian state-owned enterprises had increasingly partnered with global technology providers and engineering firms. Furthermore, through strategic bond issuances and sovereign-backed financial arrangements, Inalum successfully raised billions of dollars on international capital markets to fund the acquisition without placing an unsustainable burden on the state budget.
Official Responses and Stakeholder Reactions
The strategy to leverage state-owned enterprises for the Freeport acquisition elicited diverse reactions across the political and economic spectrum.
Proponents of economic nationalism lauded the government’s approach, viewing the acquisition of mining shares as a triumph for resource sovereignty. Lawmakers from various political factions in the House of Representatives consistently pushed the executive branch to secure majority ownership, arguing that decades of extraction warranted a commanding domestic equity presence. Labor unions representing workers in Papua also expressed cautious optimism, provided that the transition of ownership guaranteed job security, safety standard improvements, and sustained regional development funds.
Conversely, some financial analysts initially expressed reservations regarding the debt burden assumed by state-owned enterprises to finance such capital-intensive acquisitions. Critics pointed out that large-scale corporate debt could impact the balance sheets of parent companies like Inalum and Antam, potentially constraining their capacity to invest in other domestic mining ventures.
In response to these financial concerns, government officials reiterated that the projected future cash flows from the Grasberg operations would comfortably service the acquisition debt over the medium to long term. Comprehensive economic modeling demonstrated that the dividend yields and tax revenues generated by PTFI would provide a steady stream of income to the state treasury, ultimately neutralizing the initial financial risks.
Broader Economic Implications and Long-Term Impact
The integration of PT Freeport Indonesia into the portfolio of Indonesian state-owned enterprises carried profound implications for the national economy, industrial downstreaming, and geopolitical standing.
First and foremost, the majority ownership transition transformed the fiscal relationship between the mining sector and the state. Instead of relying solely on royalties, corporate taxes, and export duties, the Indonesian government—through its state-owned holding structures—began capturing direct dividend revenues reflecting the entirety of operational profitability. These funds were subsequently channeled into national development programs, infrastructure projects, and regional development initiatives in Papua.
Second, the acquisition reinforced Indonesia’s ambitions regarding domestic industrial downstreaming (hilirisasi). By holding controlling stakes in major extraction enterprises, the government exerted tighter regulatory control over the processing of raw materials within national borders. This policy directly drove the construction and commissioning of massive domestic smelters, such as the Manyar smelter in Gresik, East Java, designed to process copper concentrate domestically rather than shipping raw materials abroad.
Finally, the successful navigation of the Freeport divestment process served as a precedent for subsequent natural resource negotiations in Indonesia. It demonstrated that emerging market economies could successfully renegotiate long-standing concessions with multinational corporations, transition ownership structures through structured financial engineering, and empower domestic state-owned enterprises to manage world-class extraction sites independently.
As the operational footprint of state-managed mining continued to evolve, the initial policy assertions made by financial authorities in late 2015 were validated by the structural transformation of Indonesia’s mineral sector into an engine of sovereign economic self-reliance.