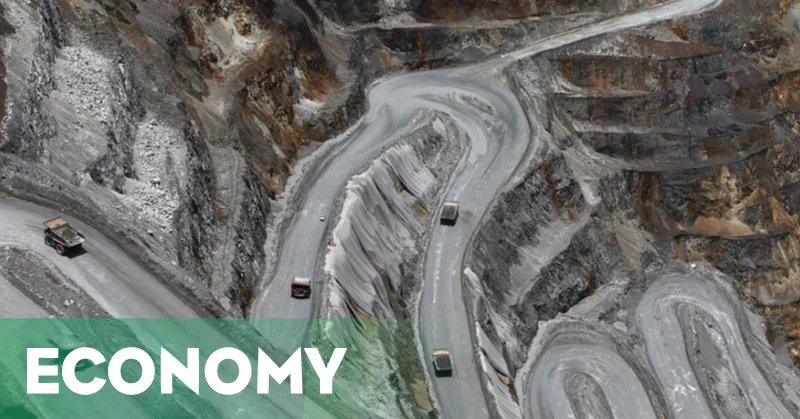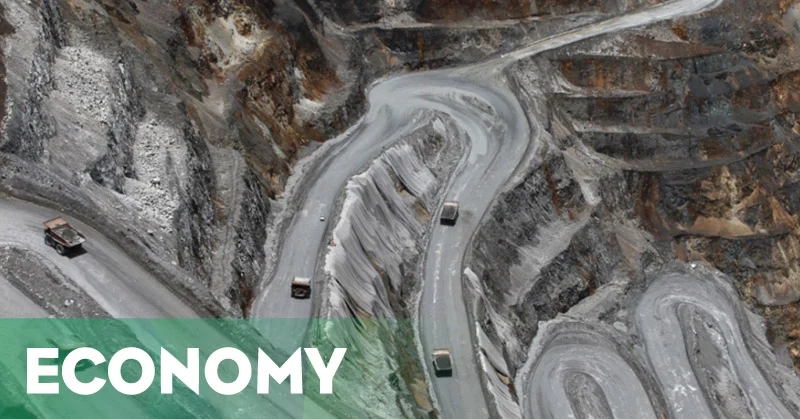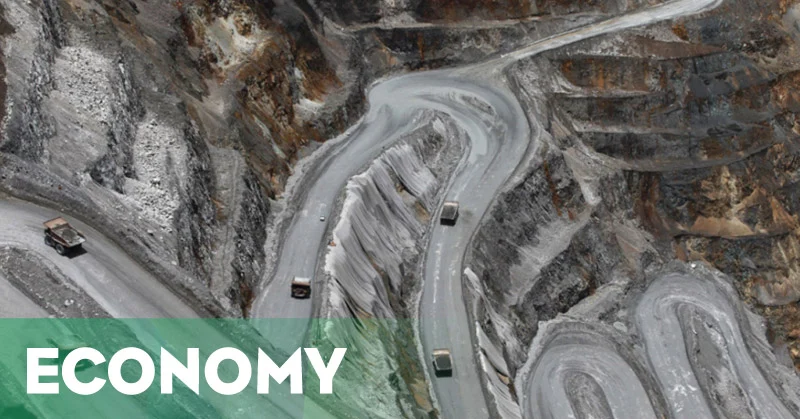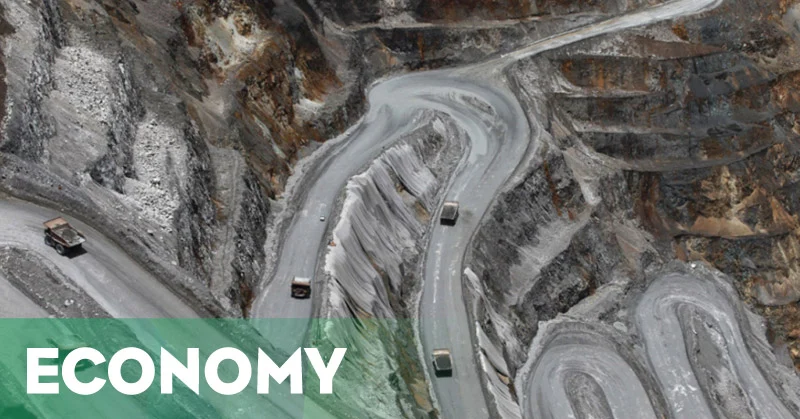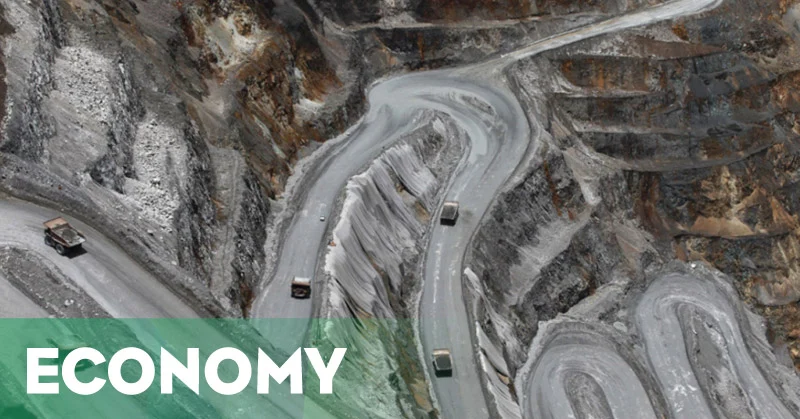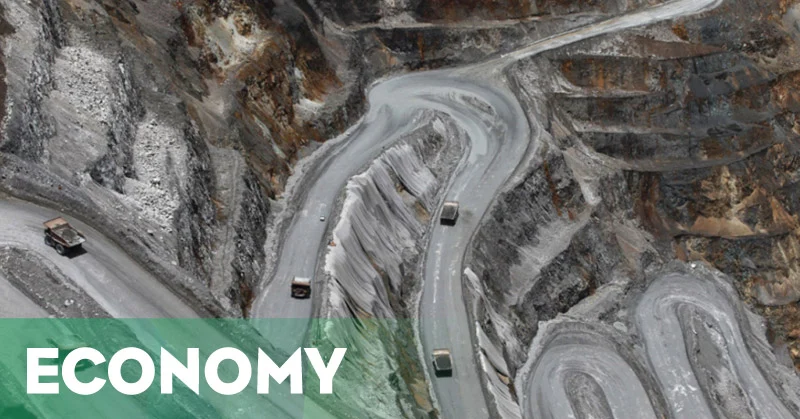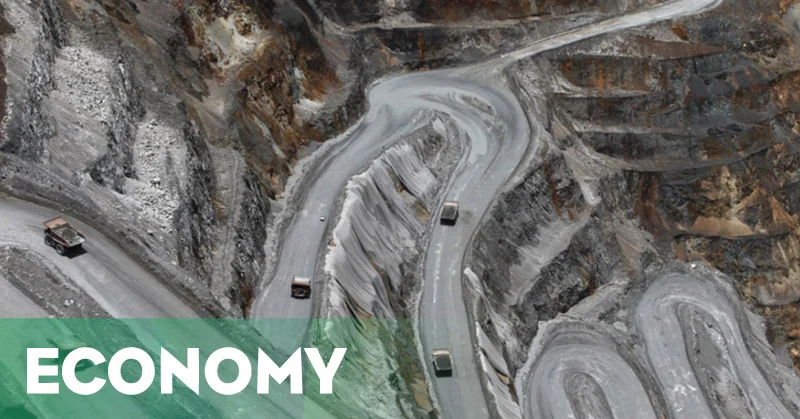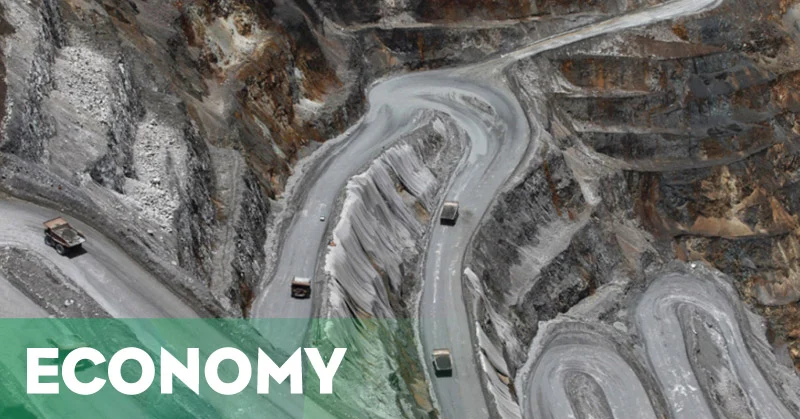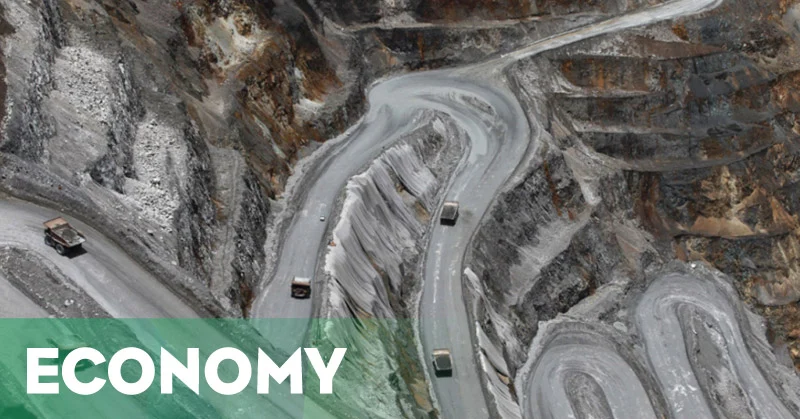
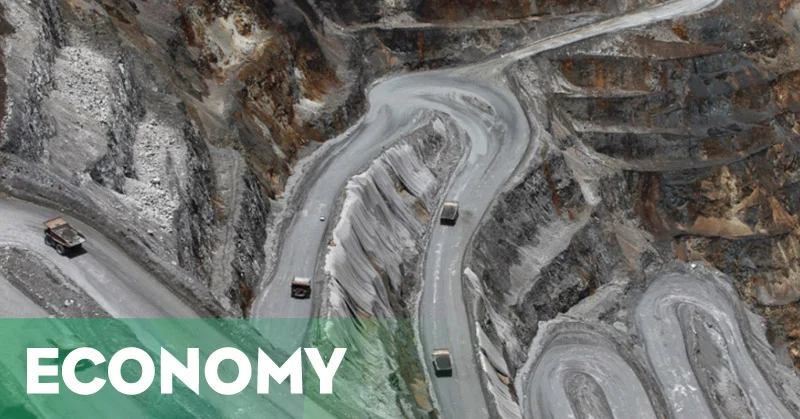
The ongoing divestment process of PT Freeport Indonesia (PTFI) has entered a critical phase, drawing significant attention from policymakers, economic experts, and the public alike as the Indonesian government moves closer to securing a greater ownership stake in the massive Grasberg gold and copper mine located in Papua. Amid discussions regarding financing, valuation, and regulatory frameworks, the central government has maintained a firm stance on the capability of state-owned enterprises to step in as primary shareholders and operational leaders. Specifically, two prominent State-Owned Enterprises (BUMN), PT Aneka Tambang (Persero) Tbk (ANTM) and PT Inalum (Persero), have been designated to spearhead the acquisition of the divested shares.
Addressing lingering doubts regarding the operational and financial readiness of these state entities, high-ranking officials have expressed unwavering confidence. Sonny Loho, who served as the Director General of State Assets at the Ministry of Finance, firmly asserted that Indonesian state-owned mining corporations possess the requisite technical expertise, managerial acumen, and financial resilience to successfully manage the vast resources of PT Freeport Indonesia. Speaking at the Ministry of Finance in Jakarta, Loho emphasized that domestic mining corporations have long proven their capabilities on both national and international stages, dismissing concerns that local entities might struggle with the sheer scale of the Freeport operations.
Background and Context of the Freeport Divestment
The push for domestic control over PT Freeport Indonesia is rooted in a long-standing nationalist economic agenda aimed at ensuring that the nation’s natural wealth provides maximum benefit to its citizens, in accordance with Article 33 of the 1945 Indonesian Constitution. For decades, the Grasberg minerals deposit—one of the largest gold and copper reserves in the world—was operated primarily by Freeport-McMoRan, a U.S.-based mining giant, through its Indonesian subsidiary, PTFI. While the operation generated substantial revenues, successive Indonesian administrations faced mounting domestic pressure to renegotiate the terms of the Contract of Work (CoW) that had governed the mining concession for generations.
The transition from a traditional Contract of Work to a Special Mining Business License (IUPK) marked a turning point in bilateral relations between the government and Freeport-McMoRan. Under the updated regulatory framework, foreign mining companies operating in Indonesia were legally mandated to divest a significant portion of their shares to Indonesian entities, progressively increasing local ownership over time. This divestment requirement was designed not only to increase state revenue through direct equity participation but also to transfer vital technological know-how and operational control to domestic enterprises.
The designation of PT Aneka Tambang (Persero) Tbk and PT Inalum (Persero) as the prime vehicles for the acquisition represented a strategic consolidation of state power within the strategic minerals sector. Antam, a diversified mining and metals company with extensive experience in nickel, gold, and bauxite mining, brought considerable operational expertise to the table. Meanwhile, Inalum—which would later evolve into MIND ID (Mining Industry Indonesia), the holding entity for state-owned mining enterprises—possessed the financial backing and capital-raising capabilities necessary to execute multi-billion-dollar corporate transactions.
Chronology of the Divestment Initiative
The journey toward nationalizing a controlling stake in PT Freeport Indonesia was characterized by protracted negotiations, complex financial valuations, and intricate legal maneuvering. The timeline of events leading up to the government’s official statements in late 2015 highlights the arduous nature of the process:
- 1967–1991: PT Freeport Indonesia initiates operations under its original generational Contract of Work, extracting massive quantities of copper, gold, and silver from the highlands of Mimika, Papua.
- 2009: The Indonesian government passes Law No. 4/2009 on Mineral and Coal Mining, introducing mandatory domestic processing and refining obligations, as well as progressive divestment rules for foreign-owned mining companies.
- 2014–2015: Tensions rise as the government enforces export bans on unprocessed minerals to encourage domestic smelter development. Negotiations begin regarding the renegotiation of the Freeport Contract of Work, which includes initial discussions on share divestment timelines.
- November 2015: Ministry of Finance officials, including Director General of State Assets Sonny Loho, publicly reiterate the government’s full confidence in state-owned enterprises such as Antam and Inalum to manage the divested shares, pushing back against skepticism from external analysts regarding state management capabilities.
- 2017–2018: Negotiations culminate in a landmark binding agreement between Inalum, Freeport-McMoRan, and Rio Tinto. Inalum agrees to acquire a 51.23% majority stake in PT Freeport Indonesia for a total transaction value of $3.85 billion.
- December 2018: The historic transaction is officially completed, with Inalum successfully funding the acquisition through international bond issuances, cementing state control over the Grasberg mine.
Addressing Skepticism and Demonstrating Readiness
During the formative stages of the divestment policy, various domestic and international market observers expressed reservations regarding the capacity of Indonesian state-owned enterprises to absorb such a massive asset. Critics pointed to the enormous capital expenditures required to maintain underground mining operations at Grasberg, as well as the specialized technological skills needed to extract minerals from high-altitude, geologically complex environments.
However, economic policymakers consistently rejected the narrative that Indonesian corporations were unprepared. Sonny Loho’s remarks underscored a broader psychological and structural shift within the Indonesian administration. By stating that local stakeholders harbored excessive apprehension, officials signaled a decisive break from decades of reliance on foreign multinational corporations for heavy resource extraction. The government maintained that Indonesian engineers, geologists, and corporate managers had accumulated decades of valuable experience working both within domestic firms and abroad, rendering them fully qualified to steer the nation’s premier mining asset.
Furthermore, the involvement of established entities like Antam ensured that deep technical knowledge of mineral processing, environmental management, and regulatory compliance would be readily available. Antam’s decades-long track record in precious metals mining provided a solid institutional foundation, while Inalum’s subsequent evolution into a strategic holding company demonstrated the government’s ability to structure sophisticated corporate financing packages.
Economic Implications and Broader Impact
The successful acquisition and management of PT Freeport Indonesia by state-owned enterprises carry profound implications for the Indonesian economy, fiscal policy, and industrial development. Transitioning a majority stake into domestic hands fundamentally alters the distribution of economic rents derived from the nation’s natural resources.
- Enhanced State Revenues: Beyond corporate taxes and royalties, the direct ownership of a 51% majority stake allows the Indonesian government to capture a substantial share of dividend distributions, directly boosting state coffers to fund infrastructure development, healthcare, and education programs.
- Downstreaming and Industrial Integration: Greater state control aligns seamlessly with Indonesia’s national industrialization policy, particularly the push for downstream processing. With domestic entities directing mining outputs, the government can more effectively mandate that raw minerals be refined locally, feeding domestic manufacturing and smelting industries rather than exporting unprocessed ore.
- Regional Development in Papua: A significant portion of the dividends generated from the divested shares is legally earmarked for distribution to the regional government of Papua and the indigenous landowners, providing crucial financial resources to accelerate local infrastructure and human capital development in the region.
- Macroeconomic Stability and Market Confidence: The successful execution of the multibillion-dollar buyout without destabilizing the national currency or exhausting state budget reserves proved the sophisticated financial capabilities of Indonesian state enterprises, enhancing international investor confidence in the country’s governance of strategic sectors.
Conclusion and Future Outlook
The strategic decision to empower state-owned enterprises to acquire and manage shares in PT Freeport Indonesia stands as a defining moment in the modern economic history of the country. What began as a contentious regulatory debate in the early 2010s ultimately transformed into a masterclass in resource nationalism executed through pragmatic corporate diplomacy and financial engineering.
As articulated by key financial officials during the formative phases of the divestment process, the transition of the Grasberg mine into state hands was not merely a symbolic victory for sovereignty, but a calculated test of institutional maturity. By systematically addressing operational, financial, and technical challenges, Indonesian state-owned enterprises have demonstrated that domestic management can successfully sustain and optimize world-class mining operations. Moving forward, the legacy of this divestment will continue to shape Indonesia’s resource policies, serving as a blueprint for future negotiations regarding foreign-owned extractive industries operating within the archipelago.