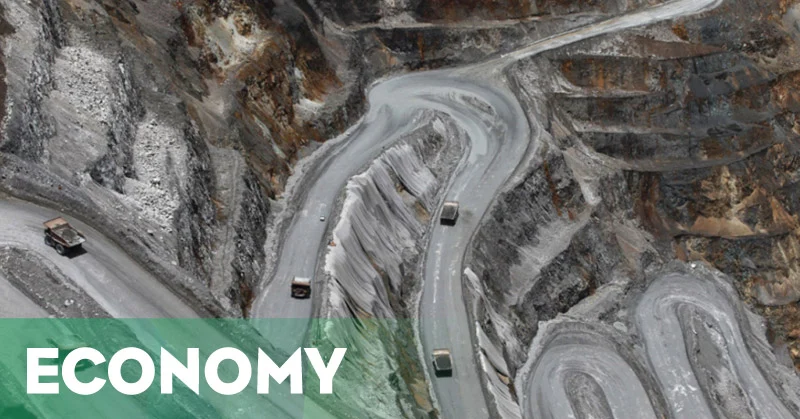
The ongoing divestment process of PT Freeport Indonesia (PTFI) marked a significant milestone as the Indonesian government prepared state-owned enterprises to acquire a larger stake in the massive mining operation in Papua. Amid public debates concerning technical competence, financial readiness, and geopolitical implications, top officials from the Ministry of Finance expressed absolute confidence in the capabilities of domestic state enterprises to manage and operate one of the world’s largest gold and copper mines.
At the forefront of this strategic acquisition are two prominent state-owned enterprises (SOEs): PT Aneka Tambang (Persero) Tbk (ANTM), commonly known as Antam, and PT Inalum (Persero). As the deadline for the divestment obligation under Freeport’s Contract of Work approached, the Ministry of Finance’s Directorate General of State Assets underscored that Indonesian corporations possessed the necessary technical prowess, operational experience, and financial backing to successfully oversee the Grasberg mineral deposit.
The official stance from the ministry sought to quell domestic skepticism, emphasizing that local mining companies had already demonstrated global-standard proficiency in managing complex extractive industries. This pivotal development reflected a broader national ambition to increase domestic control over strategic natural resources, aligning with the mandate of the Indonesian Constitution to utilize the nation’s wealth for the greatest prosperity of the people.
Background Context of the Freeport Divestment
To understand the weight of the 2015 divestment discussions, it is essential to examine the historical relationship between the Indonesian government and PT Freeport Indonesia, a subsidiary of the United States-based mining giant Freeport-McMoRan. Operating under a Contract of Work (CoW) originally signed in 1967 and renegotiated in 1991, Freeport held exclusive rights to extract vast quantities of copper, gold, and silver in the remote highlands of Mimika Regency, Papua.
For decades, the operation was predominantly foreign-owned and controlled, prompting persistent domestic criticism regarding the distribution of economic benefits, environmental stewardship, and local community development. Under the prevailing mining regulations at the time—specifically Government Regulation No. 77 of 2014 concerning the third amendment to Government Regulation No. 23 of 2010 on the implementation of mineral and coal mining business activities—foreign-owned mining companies operating underground extraction methods were legally required to divest up to 30 percent of their shares to Indonesian entities.
This regulatory framework established tiered divestment obligations: 10 percent for companies utilizing conventional open-pit mining, and up to 30 percent for underground operations like Freeport’s Grasberg complex. The process required the mining giant to progressively offer its shares to the Indonesian central government, regional governments, state-owned enterprises, regional-owned enterprises, and ultimately through national private entities via the domestic capital market.
Chronology of the Acquisition Strategy
The journey toward state ownership of PT Freeport Indonesia involved a complex sequence of negotiations, regulatory adjustments, and valuation disputes.
In early 2014, tensions rose when the Indonesian government implemented a temporary ban on raw mineral exports to encourage domestic processing through smelters. This policy directly impacted Freeport’s operations, leading to protracted negotiations over export quotas, royalty increases, taxation terms, and the divestment schedule.
By mid-2015, Freeport submitted a formal offer to divest an initial 10.64 percent stake to the Indonesian government, complying with the statutory requirement. However, the initial valuation presented by Freeport—estimated at USD 1.7 billion for the minor stake—sparked intense debate among government officials, who deemed the price excessively high.
In November 2015, the Ministry of Finance, through the Directorate General of State Assets led by Sonny Loho, clarified the operational framework for the acquisition. It was determined that two major state-owned mining and metallurgical companies, PT Antam (Persero) Tbk and PT Inalum (Persero), would act as the primary corporate vehicles to absorb the divested shares on behalf of the state. This consortium approach was designed to pool financial resources and distribute the capital expenditure burden across robust balance sheets.
Official Responses and Ministerial Stances
Addressing reporters at the Ministry of Finance in Jakarta, Director General of State Assets Sonny Loho firmly dismissed concerns regarding the technical readiness of Indonesian state-owned enterprises to manage a mega-mine like Freeport.
"Yes, they are capable. There is no reason to doubt them. Our mining companies are already performing exceptionally well," Loho stated on Wednesday, November 11, 2015.
Loho further addressed public anxiety and skepticism often echoed by local analysts regarding whether Indonesian entities possessed the engineering capability, safety standards, and managerial depth required for high-altitude block-caving underground mining. He urged domestic stakeholders to exhibit greater confidence in national capabilities.
"There is no need to worry. People in Indonesia worry too much; we must be brave. We have to be able to manage it," Loho added, reflecting the government’s resolute push toward resource nationalism and economic independence.
Financial and Operational Capabilities of Antam and Inalum
The selection of PT Aneka Tambang (Persero) Tbk and PT Inalum (Persero) as the designated acquiring entities was grounded in their extensive track records within the Indonesian mining and metals sector.
PT Antam (Persero) Tbk, established as a state-owned diversified mining and exploration company, possessed decades of expertise in nickel, gold, bauxite, and coal mining. Antam operated multiple mining sites and processing facilities across the archipelago, including the Pongkor gold mine in West Java and the Pomalaa nickel mine in Southeast Sulawesi. Its familiarity with precious metals extraction and environmental compliance made it a vital component of the consortium.
PT Inalum (Persero), meanwhile, brought heavy industrial and metallurgical experience to the table. As Indonesia’s first and largest aluminum smelting state enterprise, operating the Kuala Tanjung plant in North Sumatra, Inalum demonstrated massive energy-intensive industrial management and strategic capital allocation capabilities. Following its full acquisition by the Indonesian government from Japanese consortium shareholders in 2013, Inalum transformed into an aggressive investment arm for the state’s mining sector, eventually evolving into the holding company MIND ID (Mining Industry Indonesia).
Despite these strengths, financial analysts noted that acquiring a multi-billion-dollar stake in Freeport would require substantial external financing. Because neither Antam nor Inalum possessed idle cash reserves large enough to independently purchase double-digit equity blocks at international market valuations, the acquisition strategy necessitated syndicated loans from state-owned banks, international financial institutions, or bond issuances.
Implications and Broader Economic Impacts
The decision to position state enterprises at the helm of the Freeport divestment process carried profound implications for Indonesia’s macroeconomic landscape, fiscal policy, and foreign investment climate.
First, successful integration of PT Freeport Indonesia into the state-owned enterprise ecosystem promised a significant boost to state non-tax revenues (PNBP), dividends, and tax collections. Rather than merely collecting royalties and corporate taxes from a foreign-controlled entity, the Indonesian government stood to capture a direct share of operational profits, which could be reinvested into national infrastructure, education, and healthcare programs, particularly in Papua.
Second, the move signaled a paradigm shift in how developing nations engage with multinational extraction corporations. By asserting majority or significant equity control through domestic champions, Indonesia sought to rewrite the terms of natural resource governance. This approach balanced the need for foreign capital and advanced mining technology with the imperative of national sovereignty over strategic commodities.
Third, the transition posed distinct operational challenges. Maintaining the productivity of the Grasberg mine—which was transitioning from open-pit extraction to massive underground block-caving systems—demanded uninterrupted operational continuity, specialized engineering talent, and stringent safety protocols. Ensuring that political interference did not compromise corporate governance or technical efficiency remained a critical priority for policymakers and market observers alike.
Conclusion
The assertion by the Ministry of Finance in late 2015 that Indonesian state-owned enterprises were fully equipped to manage PT Freeport Indonesia marked a defining moment in the nation’s economic history. Through the concerted efforts of entities like PT Antam and PT Inalum, the Indonesian government laid the groundwork for enhanced domestic resource control. While financial hurdles and operational complexities remained formidable, the official resolve underscored a broader national commitment to economic self-reliance, paving the way for eventual majority state ownership and long-term prosperity derived from Papua’s subterranean wealth.