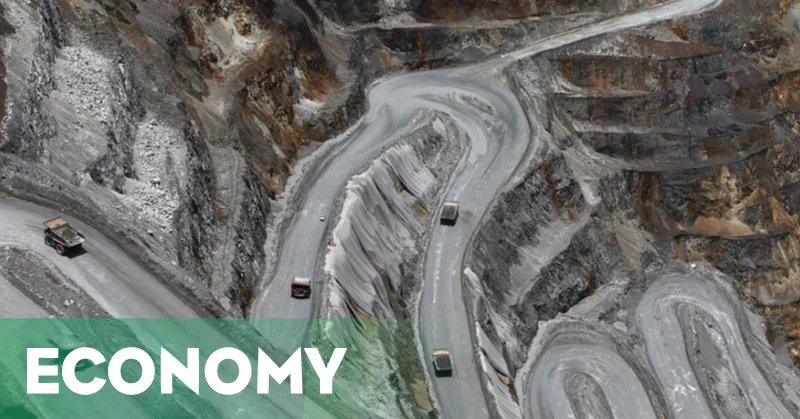
The ongoing divestment process of PT Freeport Indonesia has once again brought the country’s state-owned enterprises into sharp focus regarding the management of critical natural resources. Amidst complex negotiations and shifting regulatory landscapes, the Indonesian government has maintained a steadfast position regarding the capability of domestic entities to take on a larger stake in the massive Grasberg copper and gold mine located in Papua. Specifically, the Directorate General of State Assets at the Ministry of Finance has expressed absolute confidence that Indonesian state-owned enterprises possess the financial, technical, and operational capacity to successfully manage the vast mining concessions previously held almost exclusively by foreign capital.
As the timeline for share divestment advances, the spotlight has fallen heavily on two prominent state mining and metals corporations: PT Aneka Tambang Tbk, commonly known as Antam, and PT Inalum, which was later transformed into the holding entity MIND ID. Government officials, including senior economic policymakers, have consistently championed the narrative that national self-reliance in the extractive sector is not only a desirable policy objective but an entirely achievable reality. This perspective counters lingering skepticism from certain market analysts and international observers who have historically questioned whether local management could maintain the high production output and technological standards demanded by world-class copper and gold operations.
Background Context of the Freeport Divestment
The historical presence of PT Freeport Indonesia in the remote highlands of Papua dates back to the late 1960s, operating under successive Contracts of Work that governed its extraction rights. For decades, the majority ownership and operational control rested with the United States-based Freeport-McMoRan Inc. However, as Indonesia’s legal and political landscape matured following the reformation era, successive administrations increasingly pushed for greater national sovereignty over strategic mineral wealth, culminating in mandates embedded within the 2009 Mining Law and subsequent regulatory revisions.
A pivotal turning point arrived with the issuance of Government Regulation No. 1 Tahun 2017, which required holders of older mining contracts to convert their legal frameworks into Special Mining Business Licenses, known locally as IUPK. Crucially, this transition was legally tied to the obligation of foreign mining companies to divest up to 51 percent of their shares to Indonesian entities—encompassing the central government, regional governments, and state-owned enterprises—at fair market value. This requirement transformed the long-standing debate from a simple taxation and royalty dispute into a complex structural transformation of corporate ownership, where state-owned enterprises were designated as the primary vehicles for acquiring the mandated equity shares.
Chronology of State-Owned Enterprise Involvement
The journey toward state acquisition of PT Freeport Indonesia shares involved intricate multi-year negotiations, legal maneuvering, and corporate restructuring. The framework for the eventual takeover began to solidify in late 2015 when high-ranking officials from the Ministry of Finance, the Ministry of State-Owned Enterprises, and various related agencies actively evaluated the readiness of domestic institutions to absorb the massive financial liabilities and equity transfer values associated with the Grasberg operations.
In November 2015, high-level discussions centered on positioning PT Aneka Tambang Tbk and PT Inalum as the core consortium members designated to purchase the divested shares. At that time, the Directorate General of State Assets, led by Sonny Loho, publicly addressed domestic anxieties regarding operational continuity. Officials stressed that Indonesia’s mining sector had matured sufficiently through decades of managing complex nickel, bauxite, and coal operations, rendering the technical transition entirely manageable.
This momentum eventually paved the way for the landmark binding agreement signed in July 2018, wherein Inalum—acting on behalf of the Indonesian government—agreed to acquire a 51.23 percent majority stake in PT Freeport Indonesia through a multi-billion-dollar transaction. The financial execution of this deal was completed in late 2018 through a combination of international bond issuances and syndicated loans, effectively shifting majority control of one of the world’s largest gold and copper mines from foreign hands into the portfolio of the Indonesian state.
Official Responses and Ministerial Perspectives
Throughout the critical phases of the divestment policy, government stakeholders consistently pushed back against narratives suggesting that Indonesian corporations lacked the necessary expertise to handle deep-underground block caving mining methods utilized at Grasberg. Reassurances from the Ministry of Finance emphasized that domestic talent had been deeply integrated into the operational tiers of Freeport Indonesia for generations, meaning that a shift in shareholding ownership would not result in a sudden brain drain or operational collapse.
Speaking in Jakarta during the evaluation phases of late 2015, Directorate General of State Assets leadership strongly urged domestic critics to abandon an overly cautious mindset. Officials argued that decades of post-independence industrial development had yielded a robust cadre of mining engineers, geologists, and financial planners capable of steering multi-billion-dollar assets. The official stance was characterized by a call for national confidence, asserting that hesitation would only prolong an outdated colonial-style resource extraction model that failed to maximize domestic welfare.
Furthermore, the Ministry of State-Owned Enterprises reinforced this stance by highlighting that the consolidation of mining assets under a unified holding structure would optimize capital allocation, enhance bargaining power on global commodity exchanges, and ensure that environmental and social responsibilities in Papua were prioritized in alignment with national development goals.
Financial Structuring and Operational Readiness
The viability of state management depended heavily on innovative corporate finance strategies. Acquiring a majority stake in an asset as capital-intensive as Freeport Indonesia required marshaling immense financial resources that single state entities could rarely shoulder independently. Consequently, the orchestration of the acquisition relied on the sovereign credit strength of the state, utilizing global debt capital markets to raise funds without excessively straining the state budget.
From an operational standpoint, integration into the state-owned holding ecosystem meant that PT Freeport Indonesia would no longer operate in an isolated corporate enclave. Instead, its vast revenues could be strategically synchronized with downstream processing initiatives, such as domestic smelting projects mandated by the Indonesian government. By compelling the mining giant to build and utilize local smelters—such as the massive facilities established in Gresik, East Java—the state ensured that value addition occurred domestically rather than being exported solely as raw concentrate.
Technical readiness was another focal point of exhaustive audits. Independent engineering reviews commissioned during the divestment period confirmed that the transition from open-pit mining to underground block caving—a complex, high-risk, and highly technical extraction method—was already being executed by a workforce largely comprising Indonesian nationals. Thus, altering the ultimate parent company ownership structure would cause minimal disruption to day-to-day subterranean operations.
Broader Economic Impact and Strategic Implications
The successful integration of PT Freeport Indonesia into the state-owned enterprise portfolio carries profound implications for Indonesia’s macroeconomic stability and long-term industrial strategy. By securing majority ownership, the Indonesian government transformed a perennial source of political friction into a massive generator of state revenue, flowing directly through corporate dividends, taxes, and non-tax state revenues into the national treasury.
At the regional level, the arrangement guaranteed that the Papuan provincial government and indigenous landowning communities received a direct equity participation interest, specifically a 10 percent non-dilutable share of ownership. This mechanism was designed to foster more equitable wealth distribution and mitigate historical grievances related to environmental degradation and economic disparity in the easternmost province of the archipelago.
Moreover, the precedent set by the Freeport divestment fundamentally reshaped how foreign multinational corporations negotiate resource extraction contracts in Indonesia. It signaled to the global mining community that future investments must align with national interest frameworks, emphasizing local value creation, technology transfer, and majority national equity participation.
In conclusion, the unwavering confidence expressed by financial authorities in late 2015 regarding the capability of entities like Antam and Inalum laid the foundational psychological and structural groundwork for one of the most significant resource nationalization achievements in modern Indonesian history. What began as debated policy projections ultimately materialized into a restructured corporate reality, permanently anchoring the nation’s mineral wealth under domestic management and steering the country toward greater economic independence.