
The Indonesian economy faces a precarious intersection of capital market volatility and currency instability, as warned by Hashim Djojohadikusumo, Special Envoy of the President for Energy and Climate and Advisor to the Indonesian Chamber of Commerce and Industry (Kadin). Speaking at the Kadin National Leadership Meeting (Rapimnas) in Jakarta on Thursday, October 29, 2026, Djojohadikusumo articulated a sobering projection: the Indonesian Rupiah could face a severe depreciation, potentially reaching levels between Rp20,000 and Rp22,000 against the US dollar. This stark warning is rooted in concerns over the integrity of the domestic stock exchange and the subsequent threat of mass capital flight by international investors.
The MSCI Catalyst and Market Integrity Concerns
At the core of this potential financial crisis is the status of Indonesia within the Morgan Stanley Capital International (MSCI) global indices. The MSCI, a leading provider of critical decision support tools and services for the global investment community, has signaled reservations regarding the Indonesian market. These concerns stem from the perceived lack of transparency and the structural integrity of the Jakarta Stock Exchange.
Djojohadikusumo highlighted that international institutional investors are increasingly wary of the "free float" limitations and what he described as irrational Price-to-Earnings (P/E) ratios among several listed companies. When an index provider like MSCI contemplates downgrading a market to a "standalone" status—effectively isolating it from the broader emerging market indices—it triggers an automatic reallocation of capital by global funds. Such an exodus would necessitate a massive sell-off of Indonesian assets, putting immense downward pressure on the Rupiah.
Anomaly in Market Valuation and ‘Pump-and-Dump’ Practices
The skepticism from the global financial community is not unfounded. For several quarters, market analysts have observed anomalies in the price movements of specific emiten (listed companies) that do not appear to correlate with their fundamental financial performance. Djojohadikusumo did not shy away from addressing the "elephant in the room," acknowledging that there are widespread indications of market manipulation, colloquially referred to as "saham gorengan" or "fried stocks."
These manipulative practices involve artificially inflating the value of a stock to entice retail investors before orchestrating a collapse. Such volatility, when seen at scale, erodes the credibility of the Indonesian capital market. When global investors identify that a market’s pricing mechanism is compromised by systemic manipulation, they divest to preserve capital. The withdrawal of foreign liquidity is the primary engine behind the forecasted depreciation of the local currency.
Chronology of Currency Pressure
The vulnerability of the Rupiah is not a new phenomenon, but the current escalation represents a critical juncture. The trajectory of the Rupiah over the past 24 months has been characterized by episodic volatility.
- Q1 2025: Initial concerns regarding global interest rate hikes by the US Federal Reserve began putting pressure on emerging market currencies, including the IDR.
- Q4 2025: The Rupiah touched record lows of Rp18,180 per USD, prompting interventions by Bank Indonesia (BI) to stabilize the market.
- Mid-2026: MSCI began conducting a periodic review of the Indonesian market, signaling potential reclassification due to liquidity and governance concerns.
- October 29, 2026: Djojohadikusumo formally addresses the Kadin Rapimnas, highlighting the risk of a "run" on Indonesian assets if reforms are not implemented.
Economic Implications: The Burden of External Debt
The consequences of a currency devaluation to the level of Rp21,000 are profound. As a developing nation, Indonesia carries a significant volume of sovereign and corporate debt denominated in foreign currencies, primarily the US dollar. A weakening Rupiah effectively inflates the principal and interest payments for these obligations in local currency terms.
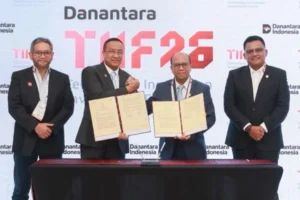
During the Rapimnas, Djojohadikusumo conferred with Minister of Investment and CEO of Danantara, Rosan Perkasa Roeslani, regarding the fiscal strain this would place on the national budget. High-profile business figures, including Chairman of the Lippo Group James Riady, were present as the warning was issued. The consensus among the leadership is that a depreciation of this magnitude would act as a regressive tax on the economy, reducing the purchasing power of the middle class, increasing the cost of imported raw materials, and potentially stalling industrial growth.
Official Responses and the Role of Bank Indonesia
While Djojohadikusumo serves as an advisor to the government, his warnings are being taken seriously by financial regulators. Bank Indonesia has traditionally maintained a policy of "triple intervention"—operating in the spot market, the Domestic Non-Deliverable Forward (DNDF) market, and the secondary market for government bonds—to mitigate excessive volatility.
However, market observers note that monetary policy alone may be insufficient if the underlying issue is a structural loss of confidence in the stock exchange. There is a growing call for the Financial Services Authority (OJK) to implement stricter oversight on suspicious trading patterns. Strengthening the "free float" requirements—the portion of a company’s shares that are in the hands of public investors—is seen as a vital step to prevent price manipulation by concentrated ownership groups.
Strategic Recommendations for Market Stabilization
To avert the scenario of a Rp21,000 exchange rate, experts suggest a multi-pronged approach:
- Regulatory Reform: The OJK must enforce stricter penalties for insider trading and market manipulation. Improving the transparency of corporate governance will be essential to regain MSCI’s confidence.
- Market Deepening: Encouraging the listing of more state-owned enterprises (SOEs) with strong fundamentals can increase the depth of the market and reduce the impact of speculative volatility.
- Monetary Discipline: Continued coordination between the Ministry of Finance and Bank Indonesia to maintain fiscal prudence and manage inflation expectations.
- Investor Relations: The government must engage in proactive communication with index providers like MSCI to outline the roadmap for market reform, thereby preventing a sudden reclassification.
Macro-Financial Analysis: A Warning, Not a Prediction
It is important to categorize Djojohadikusumo’s statements as a risk assessment rather than an inevitability. The Rp21,000 threshold serves as a "worst-case scenario" benchmark, intended to spur policymakers and industry leaders into action. The Indonesian economy has shown resilience in the past, bolstered by strong commodity exports and a robust domestic consumption base.
However, the global financial landscape is increasingly sensitive to governance standards. The days when emerging markets could rely solely on high interest rates to attract capital are fading; today’s investors prioritize transparency and the rule of law. If Indonesia fails to address the "fried stock" phenomenon and the structural limitations of its bourse, the threat of capital flight will remain a persistent shadow over the Rupiah.
Conclusion: The Path Forward
The warning issued at the Kadin Rapimnas underscores a critical realization: the health of the Rupiah is inextricably linked to the integrity of the nation’s financial institutions. As Indonesia seeks to position itself as a top-tier destination for foreign direct investment, it must reconcile its aspirations with the realities of its market operations.
Addressing the concerns of the MSCI and international investors is not merely an exercise in compliance; it is a necessary defense against a systemic financial crisis. The coming months will be decisive as the government evaluates potential reforms to the capital market infrastructure. Whether the Rupiah holds its current ground or succumbs to the pressure described by Djojohadikusumo will depend on the speed and efficacy of the measures taken to restore market sanity. For now, the business community remains on high alert, waiting to see if the proposed structural changes will materialize before the risk of capital flight becomes an economic reality.