The Indonesian Directorate General of Taxes (DJP) under the Ministry of Finance has officially recorded 1,460 corporate taxpayers as part of multinational enterprise groups that have registered under the Global Anti-Base Erosion (GloBE) rules. This significant milestone marks Indonesia’s proactive integration into the international tax architecture, specifically regarding the Pillar Two initiative spearheaded by the Organization for Economic Cooperation and Development (OECD). By formalizing these registrations through the Coretax administration system, Indonesia is ensuring that large multinational corporations operating within its borders adhere to the global minimum corporate tax rate of 15%.
The Genesis of the Global Minimum Tax
The implementation of the GloBE rules is a direct response to the "Race to the Bottom" phenomenon, where countries historically competed for foreign direct investment by lowering corporate tax rates, often leading to profit shifting and base erosion. The OECD’s Inclusive Framework on Base Erosion and Profit Shifting (BEPS) introduced the two-pillar solution to address the tax challenges arising from the digitalization of the global economy.
Pillar Two, which encompasses the GloBE rules, aims to ensure that multinational enterprises (MNEs) with annual consolidated revenues exceeding 750 million euros pay a minimum level of tax on the income arising in each jurisdiction where they operate. For Indonesia, the registration of 1,460 entities underscores the government’s commitment to curbing aggressive tax planning and ensuring a fair distribution of taxing rights among nations.
Registration Dynamics and the Coretax Portal
The registration process, as highlighted by Director General of Taxes Bimo Wijayanto, is an administrative shift that utilizes the newly operationalized Coretax system. This digital infrastructure is designed to streamline tax compliance, minimize the administrative burden on taxpayers, and enhance transparency in the reporting of global financial data.
According to the official requirements, the registration is mandatory for any constituent entity of a multinational group operating in Indonesia that meets the threshold criteria. This includes a consolidated gross revenue of at least 750 million euros, calculated based on the group’s financial statements for at least two of the four fiscal years preceding the year in which the GloBE rules are applied.
The technical execution of this registration involves the Person in Charge (PIC) of the Indonesian entity accessing the Coretax portal. By logging into the system and using the "impersonate" feature, the authorized personnel can link the corporate taxpayer’s profile to the GloBE status, thereby formalizing their compliance responsibilities within the new tax framework. This digital-first approach is expected to reduce human error and facilitate real-time monitoring by tax authorities.
Chronology of Implementation
The journey toward this current milestone did not happen overnight. Indonesia’s participation in the OECD’s BEPS framework has been a multi-year effort involving legislative reforms and bilateral negotiations.
- 2021: Indonesia joins the global consensus on the two-pillar solution, agreeing in principle to the implementation of the global minimum tax.
- 2022–2023: The Ministry of Finance conducts extensive internal reviews and stakeholder consultations to align domestic tax regulations with the OECD’s model rules.
- Early 2026: The Directorate General of Taxes initiates the rollout of the Coretax system, providing the necessary digital infrastructure to accommodate the GloBE registration requirements.
- September 2026: The DJP reports that 1,460 entities have successfully registered, signaling a high level of readiness among the target multinational corporations.
Economic Implications for Indonesia
The inclusion of 1,460 corporate taxpayers under the GloBE rules is expected to have far-reaching implications for Indonesia’s national revenue and its investment climate. Economists suggest that while the primary goal is fairness and anti-avoidance, the move also strengthens Indonesia’s fiscal sovereignty. By ensuring that these MNEs pay a top-up tax if their effective tax rate in Indonesia falls below 15%, the government can capture additional tax revenue that might otherwise have been claimed by foreign jurisdictions or avoided through tax havens.
However, the policy also presents challenges. Multinational firms are currently re-evaluating their global tax strategies. Some analysts argue that while the 15% minimum tax is a global standard, countries must balance this with non-tax incentives to remain attractive to high-quality foreign direct investment. The government has signaled that it is aware of these concerns, maintaining that the stability and transparency provided by the new tax regime will foster a more sustainable investment environment in the long run.

Official Stance and Future Outlook
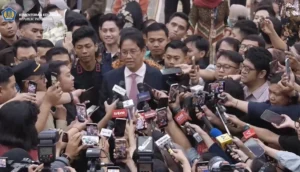
During the APBN KiTa (State Budget) press conference held on September 18, 2026, Director General Bimo Wijayanto emphasized that the 1,460 registered entities are primarily subsidiaries of ultimate parent entities (UPEs) based outside of Indonesia. This distinction is crucial, as it clarifies that the majority of the compliance burden currently involves Indonesian entities reporting their status as part of larger global structures.
"These entities represent the frontline of our compliance efforts regarding the global minimum tax," Bimo stated. He further noted that the tax authorities would continue to provide guidance and technical support to ensure that all relevant multinational groups complete their registration correctly and timely.
The Ministry of Finance intends to utilize the data collected through the Coretax portal to conduct more rigorous risk assessments. By identifying gaps between the tax paid and the 15% benchmark, the DJP can better target its audit and enforcement resources. Furthermore, the cooperation between Indonesia and other tax jurisdictions through the Exchange of Information (EOI) mechanism will be strengthened, providing the DJP with the necessary data to verify the financial claims made by these multinational groups.
Challenges in Global Tax Enforcement
The implementation of Pillar Two is not without its complexities. One of the primary challenges for the DJP is ensuring the accuracy of the financial data reported by multinational entities. Since the GloBE rules rely on consolidated financial statements, tax officers must possess a deep understanding of international accounting standards, such as IFRS (International Financial Reporting Standards).
To mitigate this, the DJP has invested in training programs for its workforce and has upgraded its data analytics capabilities. The Coretax system acts as the central hub, not just for registration, but for the entire lifecycle of tax compliance for these entities, including the filing of Global Information Returns (GIR) and the calculation of top-up taxes.
Broadening the Scope: Beyond the 1,460
While the 1,460 entities represent a significant portion of the MNE landscape in Indonesia, the tax office acknowledges that there may be other entities that fall under the threshold or have yet to finalize their registration. The government’s strategy moving forward involves a mix of taxpayer education and stricter oversight.
Tax practitioners have generally welcomed the clarity provided by the DJP, noting that a unified, digitized system like Coretax is preferable to fragmented, manual reporting. However, they also urge the government to maintain a consultative approach as the rules evolve, particularly regarding the interpretation of complex tax credits and incentives that might interact with the 15% minimum tax rate.
Conclusion
The registration of 1,460 multinational corporate taxpayers under the GloBE rules serves as a testament to Indonesia’s commitment to the global effort against tax base erosion. As the nation continues to navigate the complexities of a globalized economy, the integration of these entities into the Coretax system marks a transition toward a more transparent and equitable tax regime.
The success of this policy will ultimately be measured not just by the number of registrations, but by the effectiveness of the tax collection and the long-term impact on Indonesia’s economic stability. As the government continues to refine its regulatory framework, the collaboration between the Ministry of Finance, multinational corporations, and international tax bodies remains essential for navigating the changing landscape of global taxation. The path forward involves continuous monitoring, adaptation to international standards, and a steadfast dedication to maintaining a tax system that is both competitive and compliant with the highest global benchmarks.