The rapid evolution of artificial intelligence has fundamentally transformed how individuals approach
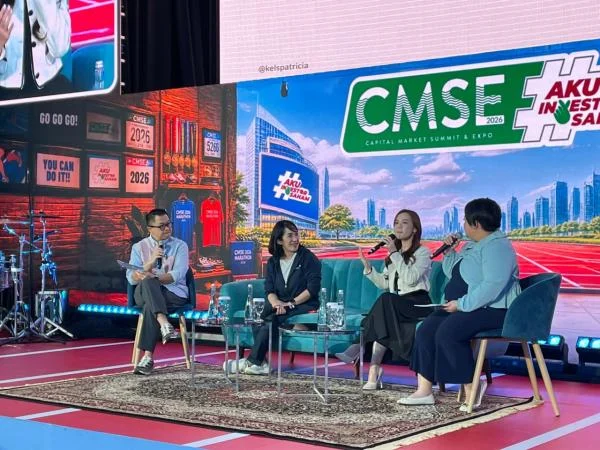
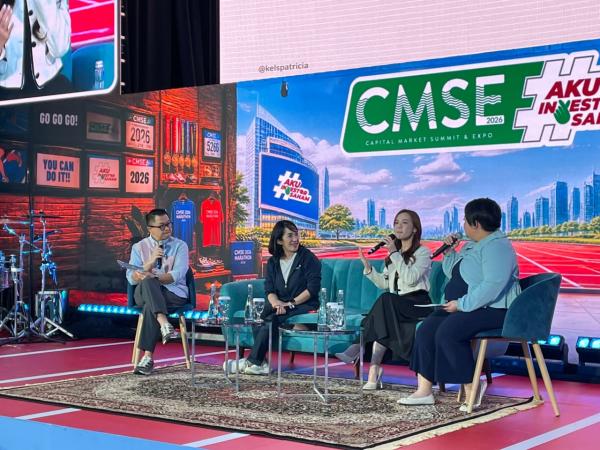
financial literacy and asset allocation, yet leveraging these advanced technologies demands rigorous critical thinking rather than passive acceptance, according to certified financial influencer Kelly Patricia. Speaking during a high-profile panel at the Capital Market Summit and Expo (CMSE) 2026, Patricia emphasized that retail investors and beginners must actively challenge AI-generated insights, understand the underlying methodologies of algorithmic models, and formulate highly structured prompts to secure actionable, reliable financial intelligence. Her remarks address a growing trend where modern market participants increasingly rely on machine learning tools, automated advisory platforms, and large language models to map out their investment journeys. While artificial intelligence offers unprecedented speed and accessibility in processing vast streams of economic data, the expert cautioned that blind reliance on automated outputs exposes unprepared market participants to severe financial miscalculations, cognitive biases, and systemic market risks.
The intersection of artificial intelligence and retail investing has accelerated dramatically over recent years, driven by the democratization of trading applications, robo-advisors, and sophisticated natural language processing tools. Historically, retail investors faced steep barriers to entry, including limited access to comprehensive market research, high advisory fees, and complex financial terminology. Today, advanced AI systems can synthesize macroeconomic reports, analyze corporate earnings transcripts, and summarize complex market trends within seconds. However, this technological leap has introduced a new paradox: while information is more abundant than ever, the ability to discern high-quality, objective financial analysis from generalized or flawed algorithmic hallucinations has become increasingly challenging. Financial literacy advocates and regulatory bodies worldwide have expressed growing concern that retail traders, particularly younger demographics entering the market for the first time, may mistake the fluent, confident tone of artificial intelligence models for infallible financial truth. It was within this dynamic context that the Capital Market Summit and Expo 2026 convened industry leaders, certified planners, and technology experts to establish best practices for integrating cutting-edge tools into personal finance strategies.
Addressing an audience of digital-native investors and market analysts, Kelly Patricia dissected the mechanical relationship between human input and algorithmic output, noting that the utility of any AI model is intrinsically bound to the precision of the user’s instructions. She explained that asking overly broad or generalized questions—such as inquiring which asset class currently represents the best investment—yields generic, unverified responses that fail to account for an individual’s unique risk tolerance, time horizon, and liquidity needs.
"If we ask artificial intelligence a generic question, we must aggressively challenge the output," Patricia stated during her session at CMSE 2026. "For instance, if the model suggests a specific sector or investment strategy, we cannot simply accept it at face value. We must interrogate the system: Why did you provide that specific recommendation? What are the underlying assumptions? What is your thought process?"
This critical interrogation framework forms the cornerstone of responsible technology integration in modern finance. Patricia underscored that artificial intelligence operates on probabilistic modeling rather than human intuition or certified fiduciary duty. Consequently, algorithms synthesize patterns from historical data, which may not accurately reflect unprecedented macroeconomic shocks, sudden regulatory shifts, or black swan events. By demanding transparency from the software—effectively treating the AI model like a junior financial analyst whose work must be thoroughly reviewed—investors protect themselves against systemic blind spots.
Furthermore, Patricia highlighted the critical role of prompt engineering in shaping the quality of financial research. In the context of capital markets, prompt engineering refers to the deliberate structuring of instructions, constraints, and contextual parameters given to an artificial intelligence engine. A poorly constructed prompt leads to ambiguous, superficial answers, whereas a meticulously crafted prompt—one that specifies risk parameters, investment vehicles, regulatory frameworks, and analytical models—produces significantly more targeted and relevant data.
Despite the inherent limitations of automated tools, the financial expert firmly maintains that artificial intelligence remains an exceptionally powerful educational asset, provided users retain ultimate intellectual ownership over their financial decisions. The technology excels at demystifying complex financial concepts, explaining tax implications, breaking down financial statements, and providing historical overviews of various market cycles. For absolute beginners intimidated by traditional textbooks or formal courses, AI acts as a patient, available tutor that can tailor explanations to an individual’s specific comprehension level.
However, Patricia warned against the psychological trap of intellectual complacency. The seamless convenience of modern technology frequently fosters cognitive laziness, tempting users to outsource their critical thinking entirely to digital systems. In the high-stakes environment of capital markets, where capital preservation is paramount, abdicating decision-making responsibility to an unverified algorithm can lead to substantial portfolio degradation. Financial literacy, she argued, cannot be automated; rather, the technology should serve as a catalyst to enhance human cognition, not replace it.
The broader implications of these insights extend far beyond individual portfolio management, touching upon the future of financial advisory services, regulatory compliance, and market stability. As retail participation continues to surge, fueled by digital accessibility and algorithmic tools, regulatory bodies such as the Financial Services Authority (OJK) and stock exchanges are increasingly scrutinizing the dissemination of financial advice via digital platforms. The phenomenon of algorithm-driven herd behavior—where large segments of retail investors act simultaneously on identical AI-generated insights—poses a unique challenge to market equilibrium, potentially exacerbating market volatility during downturns.
Industry analysts suggest that the future of wealth management will not belong exclusively to human advisors or autonomous machines, but rather to a hybrid model where human judgment, emotional intelligence, and fiduciary accountability are augmented by the computational power of artificial intelligence. In this emerging paradigm, the most successful investors will be those who master the art of critical inquiry—individuals who understand how to extract valuable data from complex algorithms while maintaining the skepticism and analytical rigor required to navigate unpredictable financial markets. As events like the Capital Market Summit and Expo 2026 demonstrate, the dialogue surrounding technology and finance is shifting away from mere adoption toward disciplined, responsible, and intellectually rigorous integration.