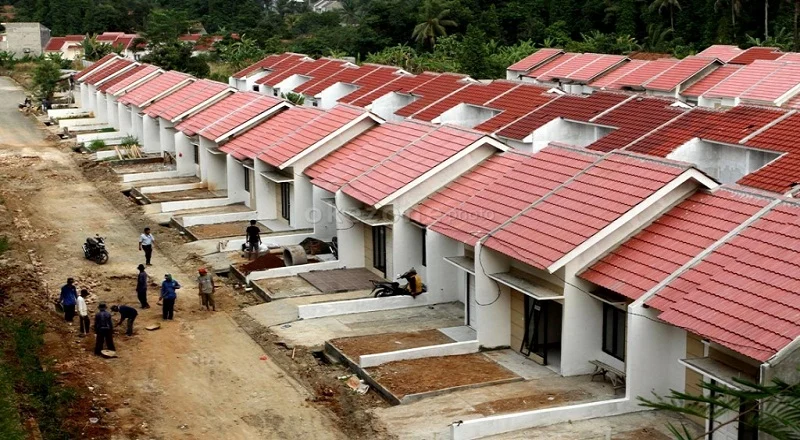
The aspiration of homeownership remains a significant hurdle for Indonesia’s younger generation, primarily due to the daunting barrier of high initial capital requirements. As of late 2026, the property market continues to face a widening gap between rising housing prices and stagnant wage growth among first-time homebuyers. Addressing this systemic challenge, Perum Perumnas—the state-owned housing developer—has officially entered into a strategic partnership with PT Bank Tabungan Negara (BTN) to launch the "Nabung DP" (Down Payment Savings) program. This initiative seeks to bridge the affordability gap by allowing prospective homeowners to accumulate their down payments through structured, incremental savings.
The Anatomy of the Housing Affordability Crisis
For many Millennials and Gen Z individuals, the primary obstacle to purchasing a home is not necessarily the ability to afford monthly installments, but the inability to provide the substantial upfront cash required for a down payment. In the current economic climate, the "backlog" of housing—the difference between the number of households and the available supply of habitable, affordable homes—remains a critical national issue. According to data from the Ministry of Public Works and Housing, the housing backlog in Indonesia has consistently hovered in the millions, with a significant portion of this demand concentrated in urban centers like Jakarta, where property appreciation consistently outpaces income growth.
The typical down payment requirement, which can range from 5% to 20% of the total property value, often represents years of aggressive saving for an entry-level worker. When combined with strict credit scoring requirements from commercial banks, many young professionals find themselves trapped in a cycle of renting, unable to satisfy the liquidity requirements necessary to secure a mortgage.
Introducing the Nabung DP Program: A Strategic Intervention
On October 29, 2026, the leadership of Perumnas and BTN unveiled the Nabung DP initiative, marking a collaborative effort to formalize the saving process for prospective homeowners. Plt Direktur Utama Perumnas, Imelda Alini Pohan, emphasized that the program is designed to transform the often-daunting task of saving into a disciplined, manageable financial habit.
The program functions as a dedicated savings vehicle where participants deposit funds systematically. These funds are held in a secure account, ensuring that the capital remains under the individual’s ownership while being earmarked for future property acquisition. This structure serves a dual purpose: it provides the necessary capital for the down payment and serves as a verified financial track record that banks can use to assess the creditworthiness of the borrower when the time comes to apply for a Mortgage Credit Facility (KPR).
Chronology and Implementation Strategy
The development of this program follows months of negotiations between the state housing developer and the nation’s leading mortgage lender. While the official launch occurred on Thursday, October 29, 2026, the groundwork for this collaboration was laid throughout the year as both institutions analyzed the failure rates of KPR applications among young applicants.
- Q1 2026: Preliminary analysis identifies that over 40% of mortgage application rejections in the affordable housing segment were due to insufficient initial capital or lack of documented financial consistency.
- Q2 2026: Perumnas and BTN initiate task forces to create a product that combines property selection with a savings mechanism.
- Q3 2026: Finalization of the regulatory framework and digital integration between Perumnas’s housing inventory systems and BTN’s savings platforms.
- October 29, 2026: Formal launch of the Nabung DP program, aimed at facilitating a smoother transition from renting to owning for the productive-age demographic.
Financial Literacy and Bank Assessment
One of the most innovative aspects of the Nabung DP program is its impact on the bank’s internal credit assessment process. In the traditional mortgage model, banks often look at salary slips and historical savings as indicators of future payment capability. By participating in the Nabung DP program, applicants provide the bank with a direct, observable pattern of financial behavior.
Imelda Alini Pohan noted that this structured saving approach is "a step that allows the bank to see the applicant’s commitment and ability to manage recurring payments, which is a vital component of successful long-term mortgage repayment." By building this habit, the applicant essentially "pre-qualifies" themselves, reducing the risk profile for the bank and potentially increasing the likelihood of loan approval.

Broader Economic Implications
The housing sector is a critical pillar of the Indonesian economy, often serving as a multiplier for various downstream industries, including construction, furniture, and financial services. When young people are unable to purchase homes, it ripples through the economy, delaying family formation and reducing long-term wealth accumulation.
Analysts suggest that the Nabung DP program could serve as a model for other developers and financial institutions to follow. By decoupling the purchase decision from the immediate requirement of a large cash sum, the program effectively lowers the barrier to entry without compromising the financial health of the banking system. Furthermore, it addresses the psychological barrier of homeownership, where the "mountain" of a down payment often discourages potential buyers from even starting the process.
Challenges and Future Considerations
While the Nabung DP program offers a promising pathway, experts note that its success will depend on several external factors, including interest rate stability and the sustained supply of affordable housing units. Inflationary pressures on building materials could potentially push housing prices higher, potentially making the savings target a "moving goalpost" for participants.
Furthermore, for the program to achieve mass-market penetration, it must be supported by transparent digital platforms that allow users to track their progress and link their savings directly to specific housing projects. The integration of technology in this space is vital for the target demographic—tech-savvy young professionals who prioritize accessibility and real-time data.
The Role of Stakeholder Synergy
The partnership between Perumnas and BTN represents a rare alignment of state-owned entities to solve a structural social issue. Perumnas, as a developer, provides the supply—the physical houses—while BTN provides the financial conduit. This synergy is essential because, in the past, the disconnect between developers and banks often left the consumer to navigate a fragmented process. By synchronizing their efforts, they have created a more cohesive "ecosystem" for the homebuyer.
Industry observers also point to the potential for government intervention, such as tax incentives or interest rate subsidies, to be integrated into programs like Nabung DP in the future. If the program proves successful in increasing the homeownership rate among the youth, it could become a central pillar of the national housing strategy.
Conclusion: A Step Toward Inclusive Urban Living
The Nabung DP initiative represents more than just a savings account; it is a tactical response to the structural challenges of the 2026 property market. By shifting the paradigm from "I can’t afford a home" to "I am saving for my home," the program empowers a generation that has felt increasingly alienated from the property market.
As the program moves into its operational phase, the focus will shift to execution and scale. For the thousands of young Indonesians looking to secure their first property, the Nabung DP program offers a structured, transparent, and disciplined path toward achieving one of life’s most significant milestones. While it is not a "magic bullet" that will erase the housing backlog overnight, it is a significant, data-driven step toward a more inclusive and accessible housing market. The success of this collaboration will likely serve as a benchmark for future public-private partnerships in the real estate sector, setting a precedent for how developers and lenders can collectively address the evolving needs of the modern homebuyer.