JAKARTA — The ongoing negotiations regarding the extension of the mining contract and subsequent share divestment for PT Freeport Indonesia
remain far from finalized, according to Coordinating Minister for Economic Affairs Darmin Nasution. Speaking at the Universitas Indonesia on Monday, November 9, 2015, Minister Darmin emphasized that administrative and substantive evaluations concerning the American mining giant’s operational future in Papua are still progressing through official government channels.
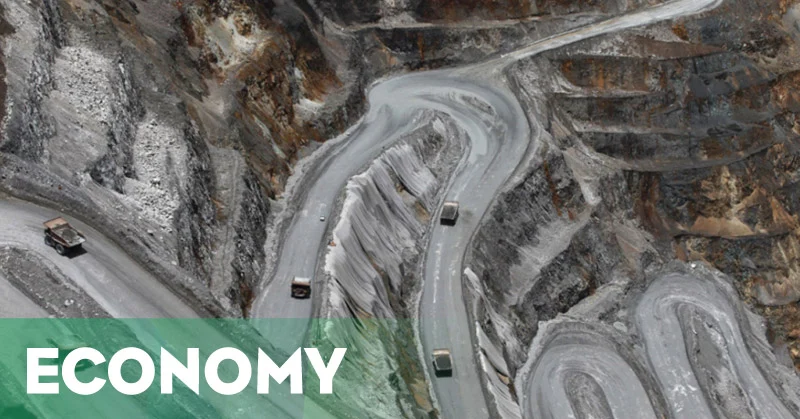
The statement underscores the complexity surrounding the multi-billion-dollar mining operations in Mimika, Papua, where Freeport-McMoRan operates one of the world’s largest gold and copper reserves. As policymakers navigate the intricate balance between national sovereignty over natural resources, foreign investment climate, and regulatory compliance, the timeline for contract renewal and mandatory share divestment has faced continuous scrutiny from both government officials and the public.
The Core of the Divestment Debate
At the heart of the current discussions is the obligation of PT Freeport Indonesia to divest a portion of its shares to Indonesian entities. According to government stipulations, October 14, 2015, marked a critical juncture when Freeport was expected to officially initiate the offering of its shares to the Indonesian government. The proposed divestment entails transferring 10.64 percent of the company’s total shares.
However, implementation has encountered regulatory and procedural bottlenecks. The United States-based mining corporation reportedly delayed the divestment process while awaiting the formal revision of Government Regulation (PP) Number 77 of 2014 concerning the third amendment to Government Regulation Number 23 of 2010 on the Implementation of Mineral and Coal Mining Business Activities. This regulation governs crucial aspects such as foreign ownership limits, divestment schedules, and domestic processing obligations.
Minister Darmin noted that the mechanics of how the divestment will be executed—whether through an Initial Public Offering (IPO) or direct placement—require exhaustive evaluation. "That must be studied more deeply," Darmin stated, highlighting the necessity for inter-ministerial coordination before any definitive financial mechanism is approved.
Regulatory Hierarchy and Priority of Share Acquisition
Under Indonesian mining regulations, the acquisition of divested shares from foreign mining companies follows a strictly regulated priority scale designed to maximize national and local ownership benefits.
- Central Government: The primary priority is given to the central government of the Republic of Indonesia.
- State-Owned Enterprises (BUMN): Should the central government decline or partially absorb the shares, the opportunity passes to state-owned enterprises.
- Regional-Owned Enterprises (BUMD): The third tier of priority is allocated to provincial or regional government-owned enterprises, particularly those operating within the jurisdiction of the mining activities, such as Papua or Mimika regional entities.
- Private National Entities and IPO: If public sector entities do not absorb the total offered shares, the remaining portion can be offered to national private entities, including through public listings on the Indonesia Stock Exchange (IDX) via an IPO.
This structured framework is designed to ensure that the wealth generated from Indonesia’s natural resources increasingly benefits domestic stakeholders, aligning with the mandate of Article 33 of the 1945 Constitution, which dictates that land, water, and natural riches shall be controlled by the state and used for the greatest prosperity of the people.
Background and Chronological Context of the Freeport Contract
The relationship between the Indonesian government and Freeport spans several decades, originating with the initial Contract of Work (CoW) signed in 1967, shortly after the enactment of the country’s first Foreign Investment Law. A second-generation Contract of Work was signed in 1991, extending Freeport’s operations through 2021, with provisions for two potential 10-year extensions up to 2041.
As the 2021 expiration date approached, discussions regarding the terms of future operations intensified significantly. Under the 2009 Mining Law (UU No. 4/2009), foreign mining companies operating under older Contracts of Work were required to transition into Special Mining Business Licenses (IUPK), commit to domestic processing and refining (smelting), and divest up to 51 percent of their shares to Indonesian participants over a phased timeline.
The tension between Freeport’s contractual rights under its 1991 CoW and the stricter mandates of the 2009 Mining Law became a focal point of economic and legal debate. While Freeport argued for legal and fiscal certainty guaranteed under its existing contract, the Indonesian government insisted on the primacy of national laws enacted subsequently.
Economic and Fiscal Implications
The delay in resolving the Freeport contract extension and divestment process carries broad implications for both the national economy and regional development in Papua. PT Freeport Indonesia has historically been one of the largest corporate taxpayers in Indonesia, contributing significantly to non-tax state revenues (PNBP), corporate income taxes, royalties, and regional development funds.
Furthermore, the uncertainty surrounding the regulatory framework affects investor confidence in the broader mining sector. International mining investors closely monitor how Indonesia handles long-standing foreign contracts, balancing the desire for resource nationalism and increased state revenue with the need for stable, predictable regulatory environments that attract foreign direct investment (FDI) for capital-intensive projects.
Energy and mining analysts point out that the divestment valuation itself has been a point of contention. Valuing multi-billion-dollar underground and open-pit mining assets involves complex assessments of future commodity prices (particularly copper and gold), reserve life, environmental liabilities, and infrastructure investments. Determining whether the central government, local governments, or state-owned enterprises possess the fiscal capacity to purchase these shares without straining state budgets remains a critical policy challenge.
Stakeholder Perspectives and Institutional Positions
Various government bodies hold distinct responsibilities in managing the Freeport relationship. The Ministry of Energy and Mineral Resources (ESDM) handles the technical, licensing, and regulatory compliance aspects of the mining operations. Meanwhile, the Coordinating Ministry for Economic Affairs, led by figures like Darmin Nasution, oversees broader macroeconomic impacts, fiscal policies, and inter-ministerial synchronization.
Simultaneously, regional governments in Papua have continually voiced expectations for a larger stake in the mining operations. Local stakeholders argue that decades of resource extraction have left profound environmental and social footprints, necessitating greater direct economic participation and financial returns for the indigenous populations of the region.
State-owned enterprises, including mining holding entities such as PT Inalum (now MIND ID), have periodically been positioned as potential vehicles for acquiring the divested shares, reflecting a strategic shift toward consolidating national control over strategic mineral assets. However, funding mechanisms and valuation agreements must be meticulously structured to ensure commercial viability and transparency.
Broader Impact on Indonesia’s Mining Landscape
The prolonged negotiations with Freeport serve as a watershed moment for Indonesia’s mineral governance. The policy stance adopted during these discussions sets a precedent for how future foreign mining concessions are managed, particularly as older contracts approach their expiration dates.
The emphasis on domestic smelting obligations, increased local equity participation, and renegotiation of fiscal terms reflects a broader paradigm shift in Indonesian economic policy. Rather than acting merely as an exporter of raw minerals, Indonesia has sought to capture higher-value components of the global supply chain through domestic processing and industrial downstreaming.
As the administrative process continues to unfold beyond late 2015, market observers and policymakers alike await formal regulatory adjustments, particularly regarding the finalization of government regulations governing divestment procedures and foreign ownership caps. Until these regulatory parameters are definitively settled and signed into law, the ultimate trajectory of PT Freeport Indonesia’s corporate structure and contractual tenure will remain a central pillar of Indonesia’s economic and industrial policy discourse.