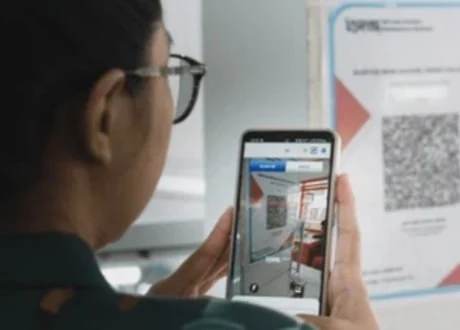
The rapid expansion of the Quick Response Code Indonesian Standard (QRIS) has fundamentally reshaped the financial landscape in Indonesia, serving as a catalyst for a broader digital transformation across the nation’s commercial sector. Data released by Bank Indonesia (BI) for the first half of 2026 highlights a seismic shift in consumer and merchant behavior, with total QRIS users reaching 65.77 million by June 2026. This mass adoption is not merely a trend but a structural evolution, as businesses increasingly prioritize operational efficiency to remain competitive in a high-velocity, non-cash economy. The total transaction volume for the first six months of 2026 reached an unprecedented 12.55 billion transactions, representing a total value of Rp1.12 quadrillion, a staggering 93.92% increase compared to the same period in the previous year.
The Evolution of the Digital Payment Ecosystem
The implementation of QRIS, introduced by Bank Indonesia in August 2019, was designed to unify various payment platforms under a single, interoperable standard. Before QRIS, the Indonesian market was fragmented, with merchants needing to display multiple QR codes for different e-wallet providers. The standard was officially launched to the public on August 17, 2019, as part of the Indonesia Payment Systems Blueprint 2025.
Over the past seven years, the ecosystem has moved from an experimental phase to a critical utility. By mid-2026, the data indicates that the integration of digital payments has moved beyond urban centers, penetrating the micro, small, and medium enterprise (MSME) segments. This ubiquity has necessitated a shift in the service model provided by payment gateways. As noted by industry experts, the primary focus for merchants has evolved from finding the cheapest transaction fees to seeking reliable, long-term partnerships that ensure continuous uptime and robust customer support.
Strategic Perspectives from Industry Players
As the digital payment market matures, the role of payment service providers (PSPs) has become increasingly complex. According to Grace Sunarjo, Chief Revenue Officer at OttoDigital, the current market climate demands a holistic approach to merchant support. "The experience of OttoPay in serving thousands of merchants over nearly a decade has proven that business owners require more than just a payment gateway with competitive pricing," said Sunarjo. "They require a strategic payment partner that offers comprehensive services."
This sentiment reflects a broader industry trend where PSPs are moving away from commodity-based service models toward value-added consulting and technical support. For many small-scale merchants, the barrier to entry for digital payments has historically been the administrative burden associated with compliance, documentation, and technical integration. By streamlining these processes, service providers are enabling a more inclusive digital economy, allowing even the smallest street-side vendors to participate in the national digital financial infrastructure.
Chronology of the QRIS Expansion
The journey toward a cashless society in Indonesia has been marked by several key regulatory and technological milestones:
- August 2019: Bank Indonesia officially launches QRIS to unify digital payment standards, aimed at increasing financial inclusion.
- 2020-2021: The COVID-19 pandemic acts as an unexpected accelerator, as public health concerns regarding physical cash handling drive an unprecedented increase in contactless payment adoption.
- 2022: Bank Indonesia introduces QRIS TUNTAS (Transfer, Tarik Tunai, Setor Tunai), allowing users to withdraw and deposit cash at ATMs or through agents using QR codes.
- 2023: The central bank pushes for cross-border QRIS, enabling Indonesian users to conduct transactions in neighboring countries like Malaysia, Thailand, and Singapore, significantly boosting tourism-related payments.
- 2024: Regulatory emphasis shifts toward security, with the implementation of more stringent fraud detection protocols and user protection frameworks.
- 2025-2026: The current phase marks the saturation of the market, where the focus shifts from user acquisition to service quality, operational stability, and high-volume transaction processing efficiency.
Data Analysis: The Surge in Transactional Value
The 93.92% year-on-year growth in transaction value to Rp1.12 quadrillion is indicative of the rising trust in digital systems. When analyzing this data, it is important to observe the ratio of transaction volume to value. With 12.55 billion transactions, the average transaction size is relatively small, which aligns with the typical usage patterns of QRIS in retail, food and beverage, and transportation sectors.
The economic implications of this surge are significant. First, the formalization of these transactions provides MSMEs with a digital footprint, which is essential for future credit scoring and access to formal financial products like micro-loans. Second, the reduction in cash handling costs—such as physical security, transport of cash, and the risk of counterfeit money—allows merchants to reinvest capital more effectively. Finally, the real-time nature of digital payments improves liquidity for businesses, as they no longer have to wait for end-of-day banking settlements to access their daily revenue.
Addressing Operational Bottlenecks
A common pain point for new merchants is the "onboarding" process. The administrative time taken to verify documentation, set up the merchant account, and activate the QR code can often be a source of frustration. OttoPay’s current strategy, which aims for an activation time of just three business days post-verification, is a response to this market demand.
The emphasis on "after-sales support" is particularly critical. In a digital-first environment, any technical outage—no matter how brief—directly impacts revenue. Merchants are increasingly prioritizing partners who can offer immediate, human-led technical assistance when transaction errors occur. This shift suggests that the competitive landscape for payment providers in late 2026 is no longer about the technology itself, which has become standardized, but about the quality of the ecosystem supporting that technology.
Broader Economic and Regulatory Implications
Bank Indonesia remains the primary architect of this transition. Its mandate is not merely to promote digital payments but to ensure the resilience of the national payment system. The central bank has been clear in its messaging: while digital payment adoption is a national goal, it must coexist with physical currency to ensure inclusivity. Recent directives from BI have explicitly stated that merchants cannot refuse cash payments, a policy aimed at preventing the marginalization of segments of the population who remain unbanked or technologically averse.
The impact of this policy is a "hybrid" payment ecosystem. For the foreseeable future, Indonesia will likely operate on a dual-track system where digital payment adoption continues to skyrocket, yet cash remains a legal and accessible alternative. This dual-track approach is vital for economic stability, especially in regions with limited internet connectivity or lower levels of digital literacy.
Future Outlook and Challenges
As Indonesia moves toward the latter half of the decade, the challenges for the QRIS ecosystem will likely evolve from mass adoption to deeper integration. Future developments are expected to include:
- Deepened Integration with Financial Services: QRIS will likely serve as the gateway for more complex financial products, such as buy-now-pay-later (BNPL) services, insurance, and investment products at the point of sale.
- Enhanced Security Frameworks: As the volume of transactions grows, so too does the risk of cyber threats. Future investments will be heavily directed toward artificial intelligence-driven fraud detection and secure multi-party computation.
- Cross-Border Scalability: Expanding the cross-border QRIS network to more nations will be a priority for the government to facilitate seamless international travel and trade.
- Merchant-Side Innovation: Merchants will seek more sophisticated data analytics tools integrated into their payment portals, allowing them to track inventory, consumer trends, and performance metrics in real-time.
In conclusion, the rise of QRIS in Indonesia is a testament to the power of standardized, interoperable technology when backed by clear regulatory foresight and industry execution. The transition to a cashless society is no longer a future prospect but a current reality, defined by billions of transactions that reflect a more efficient, transparent, and digitally empowered national economy. As businesses continue to optimize their operations through the adoption of digital tools, the focus will increasingly shift toward the quality of the partnerships that sustain this growth, ensuring that the digital payment revolution remains both sustainable and inclusive for all stakeholders.